Analysis  /  Value-Chain Series  /  Latin America
Analysis · Latin America · Copper

$4.3bn out the door.
BHP read the cycle.

BHP posted one of its best halves in years, then used it to pre-sell the future. The largest precious-metals streaming deal in history, plus two more disposals, pulls cash forward to defend a dividend the capex cycle is about to squeeze. Selling the silver was the tell.

ZMK Advisory Research 13 May 2026 10 min read Facts-First Analysis
Key points

BHP used one of its strongest halves to sell future cash flows, and owning it is now a call on the copper price through 2028.

  1. 01BHP pulled US$6.3bn of future cash forward in one of its strongest halves.Underlying EBITDA rose 25% to US$15.5bn, and copper passed half of group EBITDA for the first time. The Wheaton silver stream alone raised US$4.3bn, the largest precious-metals stream ever struck.
  2. 02The silver stream is leverage in substance, though not in form.BHP now keeps 20% of the spot silver price for the life of the mine, and the proceeds are not expected to raise reported debt.
  3. 03The capex bill is larger and the execution record weaker.Capex runs to roughly US$52bn over FY26 to FY30, and Jansen Stage 1 has overrun by 47%, from US$5.7bn to US$8.4bn.
  4. 04Free cash flow over FY26 to FY30 ranges six-fold with prices.About US$60bn at spot prices, and about US$10bn in the three-year-low scenario.
  5. 05Three lines in the August result will test the case.The FY27 capex guide, any reference to CMRG pricing, and whether the dividend is reaffirmed without conditions.
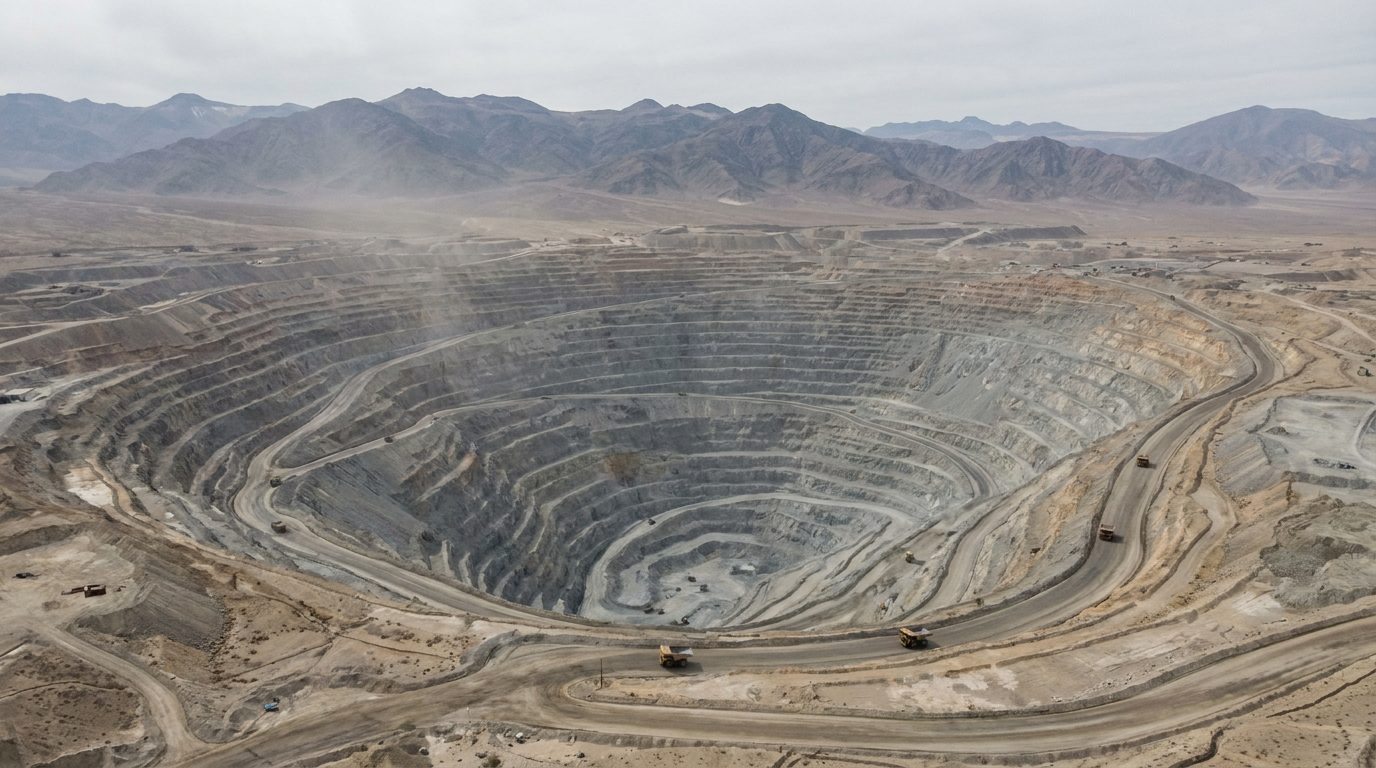
A large open-pit copper mine in the Atacama Desert
Copper now carries more than half of BHP’s earnings, and the whole of its investment case. Illustrative image.
Capital pulled forward · US$6.3bn unlocked, pathway to US$10bn
Silver stream $4.3bn
WAIO power ~$2.0bn
← to $10bn target
■ Wheaton silver stream (Antamina): $4.3bn ■ WAIO inland power (GIP): ~$2.0bn ■ Carajás divestment: $0.24bn on completion
Sources 2, 3, 4 and 5. The silver stream and the WAIO power agreement unlock US$6.3bn, with a stated pathway to about US$10bn. The Carajás sale added US$240m on completion, with up to US$225m more contingent.
01 · Context

BHP used one of its strongest halves to pull US$6.3bn of future cash forward.

On the face of it, BHP’s HY26 was one of the strongest results of Mike Henry’s tenure: underlying EBITDA of US$15.5bn, up 25%, at a 58% margin; attributable profit of US$6.2bn; and operating cash flow of US$9.4bn. 1 For the first time since BHP began reporting a copper segment, copper delivered more than half of group EBITDA, at a 66% margin, while Western Australian iron ore earned a 62% margin. 1 Net debt of US$14.7bn sat at about 0.5× annualised EBITDA on ZMK’s arithmetic, return on capital reached 23.6%, and the interim dividend was 73 US cents. 1

And yet, against that backdrop, BHP set out two agreements that together unlock US$6.3bn of cash, with a stated path to about US$10bn. 2 The headline act was a Wheaton streaming deal that sold BHP’s share of Antamina’s silver for US$4.3bn upfront, which BHP calls the most valuable streaming transaction to date. 3 Alongside it sat a US$2bn power agreement on the iron-ore business, 4 and in April the Carajás copper sale closed. 5 A month after the results, the Board named Brandon Craig, who has run much of the growth pipeline as President Americas, to succeed Henry from 1 July. 6 When a company this strong is pre-selling its cash flows, the interesting question is not the framing. It is what the numbers are telling you about the risk it now carries.

$4.3bn
Silver stream, largest to date
51%
Copper share of group EBITDA, a first
6×
Swing in five-year free cash flow
02 · Framework

The silver stream pre-sells 80% of the upside to fund a capex peak.

The most revealing line in the HY26 deck is footnoted, not headlined: the upfront proceeds from the silver stream approach the consensus NAV of BHP’s entire 33.75% stake in Antamina. 2 Read that again. BHP received, in cash, roughly what the market values the whole interest at, by selling only the silver byproduct, and keeping the copper, zinc, lead and molybdenum. Either Wheaton overpaid and BHP captured a windfall, or the sell-side has been quietly under-marking BHP’s non-operated joint ventures for years. Probably both.

But a windfall at execution is not the same as a good trade over time. The stream runs for the life of the mine, and BHP now receives just 20% of the spot silver price on every ounce delivered. 3 In other words, it has pre-sold 80% of the upside on precisely the commodity Wheaton is betting will rise. And the accounting is its own tell: management states the US$4.3bn is “not expected to increase reported debt levels.” 3 In substance, this is leverage. In form, it is not.

You do not sell your best byproduct at the top of its cycle unless you need the cash somewhere else, and BHP’s capex tells you exactly where.

The growth bill is larger and longer than the headline. BHP’s capex guidance across FY26–30 adds up to roughly US$52bn, and more once non-operated joint ventures are counted. 1 The execution record has cracked. Jansen Stage 1 was sanctioned at US$5.7bn and now stands at US$8.4bn, a 47% overrun. 1 7 BHP itself calls Jansen an outlier: its other major projects since 2013 averaged about 3% over their sanction estimates, against about 37% for the mining industry. 2

Jansen Stage 1 · sanction vs. current estimate
Sanctioned$5.7bn
Current estimate$8.4bn · +47%
Sources 1 and 7. BHP’s other major projects averaged about 3% over sanction estimate; the mining industry, about 37% (source 2).

That is why the disposals matter. Over the past decade BHP returned more than US$110bn to shareholders, around 70% of its market capitalisation, 2 and the market has priced that cadence in. On ZMK’s arithmetic through the capex peak, the distributable cash left after sustaining capital, growth, JV calls, tax and Samarco falls to roughly US$3–5bn a year, below both the decade’s pace and the implied minimum dividend. It holds at spot; it does not hold in the downside.
Cumulative attributable free cash flow, FY26–30
At spot prices~$60bn
At the three-year-low scenario~$10bn
Source 2. A six-fold range, and the whole investment case in one number. BHP’s three-year-low scenario assumes copper at US$3.50/lb and iron ore at US$80/t.
An iron-ore freight train crossing the Pilbara
The other side of the book: iron ore, and a Chinese buyer now consolidating the price. Illustrative image.
03 · Quantified Impact

Owning BHP is now a call on the copper price through 2028.

The bull case is real: BHP is among the world’s largest copper producers, with a breakeven copper price near US$1.40/lb against about US$4.00 for pure plays, average EBITDA margins above 50% over 25 years, and a target of about 2.5 Mtpa of copper-equivalent by FY35. 2 On ZMK’s estimate of roughly 6× forward EBITDA against a copper-weighted peer line nearer 8×, the equity may be 20–25% mispriced.

The bear case is sharper than consensus allows. BHP has pre-funded its capex by selling future cash flows, including its single largest byproduct stream, while lengthening its commitments, under a CEO who is also their architect. The Samarco provision stands at US$5.3bn, 1 and on 6 May the Court of Appeal in London refused BHP permission to appeal the English liability judgment. 8 And the quietly disclosed conclusion of iron-ore contract talks with China’s CMRG, a body built to consolidate Chinese buying power, 5 is a pricing risk not yet in any guidance number. It will surface in the next set of results.

What we would tell the committee

Read the silver sale for what it is: a strong operator pre-funding its distribution before a capex peak, a contested Samarco appeal, and a Chinese buyer consolidating the other side of its iron-ore book. Owning it is a copper-price conviction call through 2028, not a bet on anything BHP can control.

The next honest test is the August full-year result. Watch three lines: the FY27 capex guide and whether Jansen Stage 2 is re-sanctioned materially higher; any reference to CMRG pricing; and whether the dividend is reaffirmed without conditions, or hedged with capex-priority language. Two of the three tilt bear.

Value-Chain Series The number, then the narrative.
Sources

Each figure traces to a numbered source below. Figures marked as ZMK’s arithmetic or estimate are our own calculations from those sources.

  1. BHP, Results for the half year ended 31 December 2025, 17 February 2026. EBITDA, margins, profit, cash flow, net debt, ROCE, dividend, capex guidance, Jansen Stage 1 at US$8.4bn, Samarco provision.
  2. BHP, HY2026 Results Presentation, “Stability + Growth = Value”, 17 February 2026. US$6.3bn unlocked and pathway to US$10bn; stream proceeds against consensus NAV; project delivery against sanction; free cash flow scenarios; breakeven, margin and FY35 copper target; returns since 2016.
  3. BHP, “BHP enters into a silver streaming agreement”, 17 February 2026. US$4.3bn upfront; 20% of spot paid per ounce; life of mine; no expected increase in reported debt.
  4. BHP, “BHP enters into a US$2 billion infrastructure agreement with Global Infrastructure Partners on WAIO inland power”, 9 December 2025.
  5. BHP, Operational Review for the nine months ended 31 March 2026, 22 April 2026. Carajás completion (US$240m plus up to US$225m contingent); conclusion of contract negotiations with CMRG.
  6. BHP, “Brandon Craig to succeed Mike Henry as BHP CEO”, 18 March 2026.
  7. MINING.COM, “BHP takes $2.3B hit on Jansen as cost of potash mine swells again”, 2026. Original Stage 1 sanction of US$5.7bn in 2021.
  8. MINING.COM (Reuters), “BHP loses bid to appeal Brazil dam disaster ruling”, May 2026.
Analytical interpretation of publicly available disclosures. All analysis is opinion and not investment advice.

Related field notes

All Field Notes →