Eramet’s €2.5bn Question
The €500m rights issue is designed to clear the June 2027 covenant test. €2,513m of debt falls due in 2028 and 2029, and Eramet's roadmap of 9 November does not say how it will be refinanced. This is our sequence, updated for three months of disclosure, including one number of ours we have revised.
Built from Eramet's published accounts and releases. ZMK Advisory has not been retained by Eramet and holds no position.Follows Eighty-Three Days, August 2026 · 1080p
The six exhibits in this note, with the scorecard and the three questions for the board, as one 151 KB PDF. The fifty-page strategy deck behind them is available on request.
The answer first
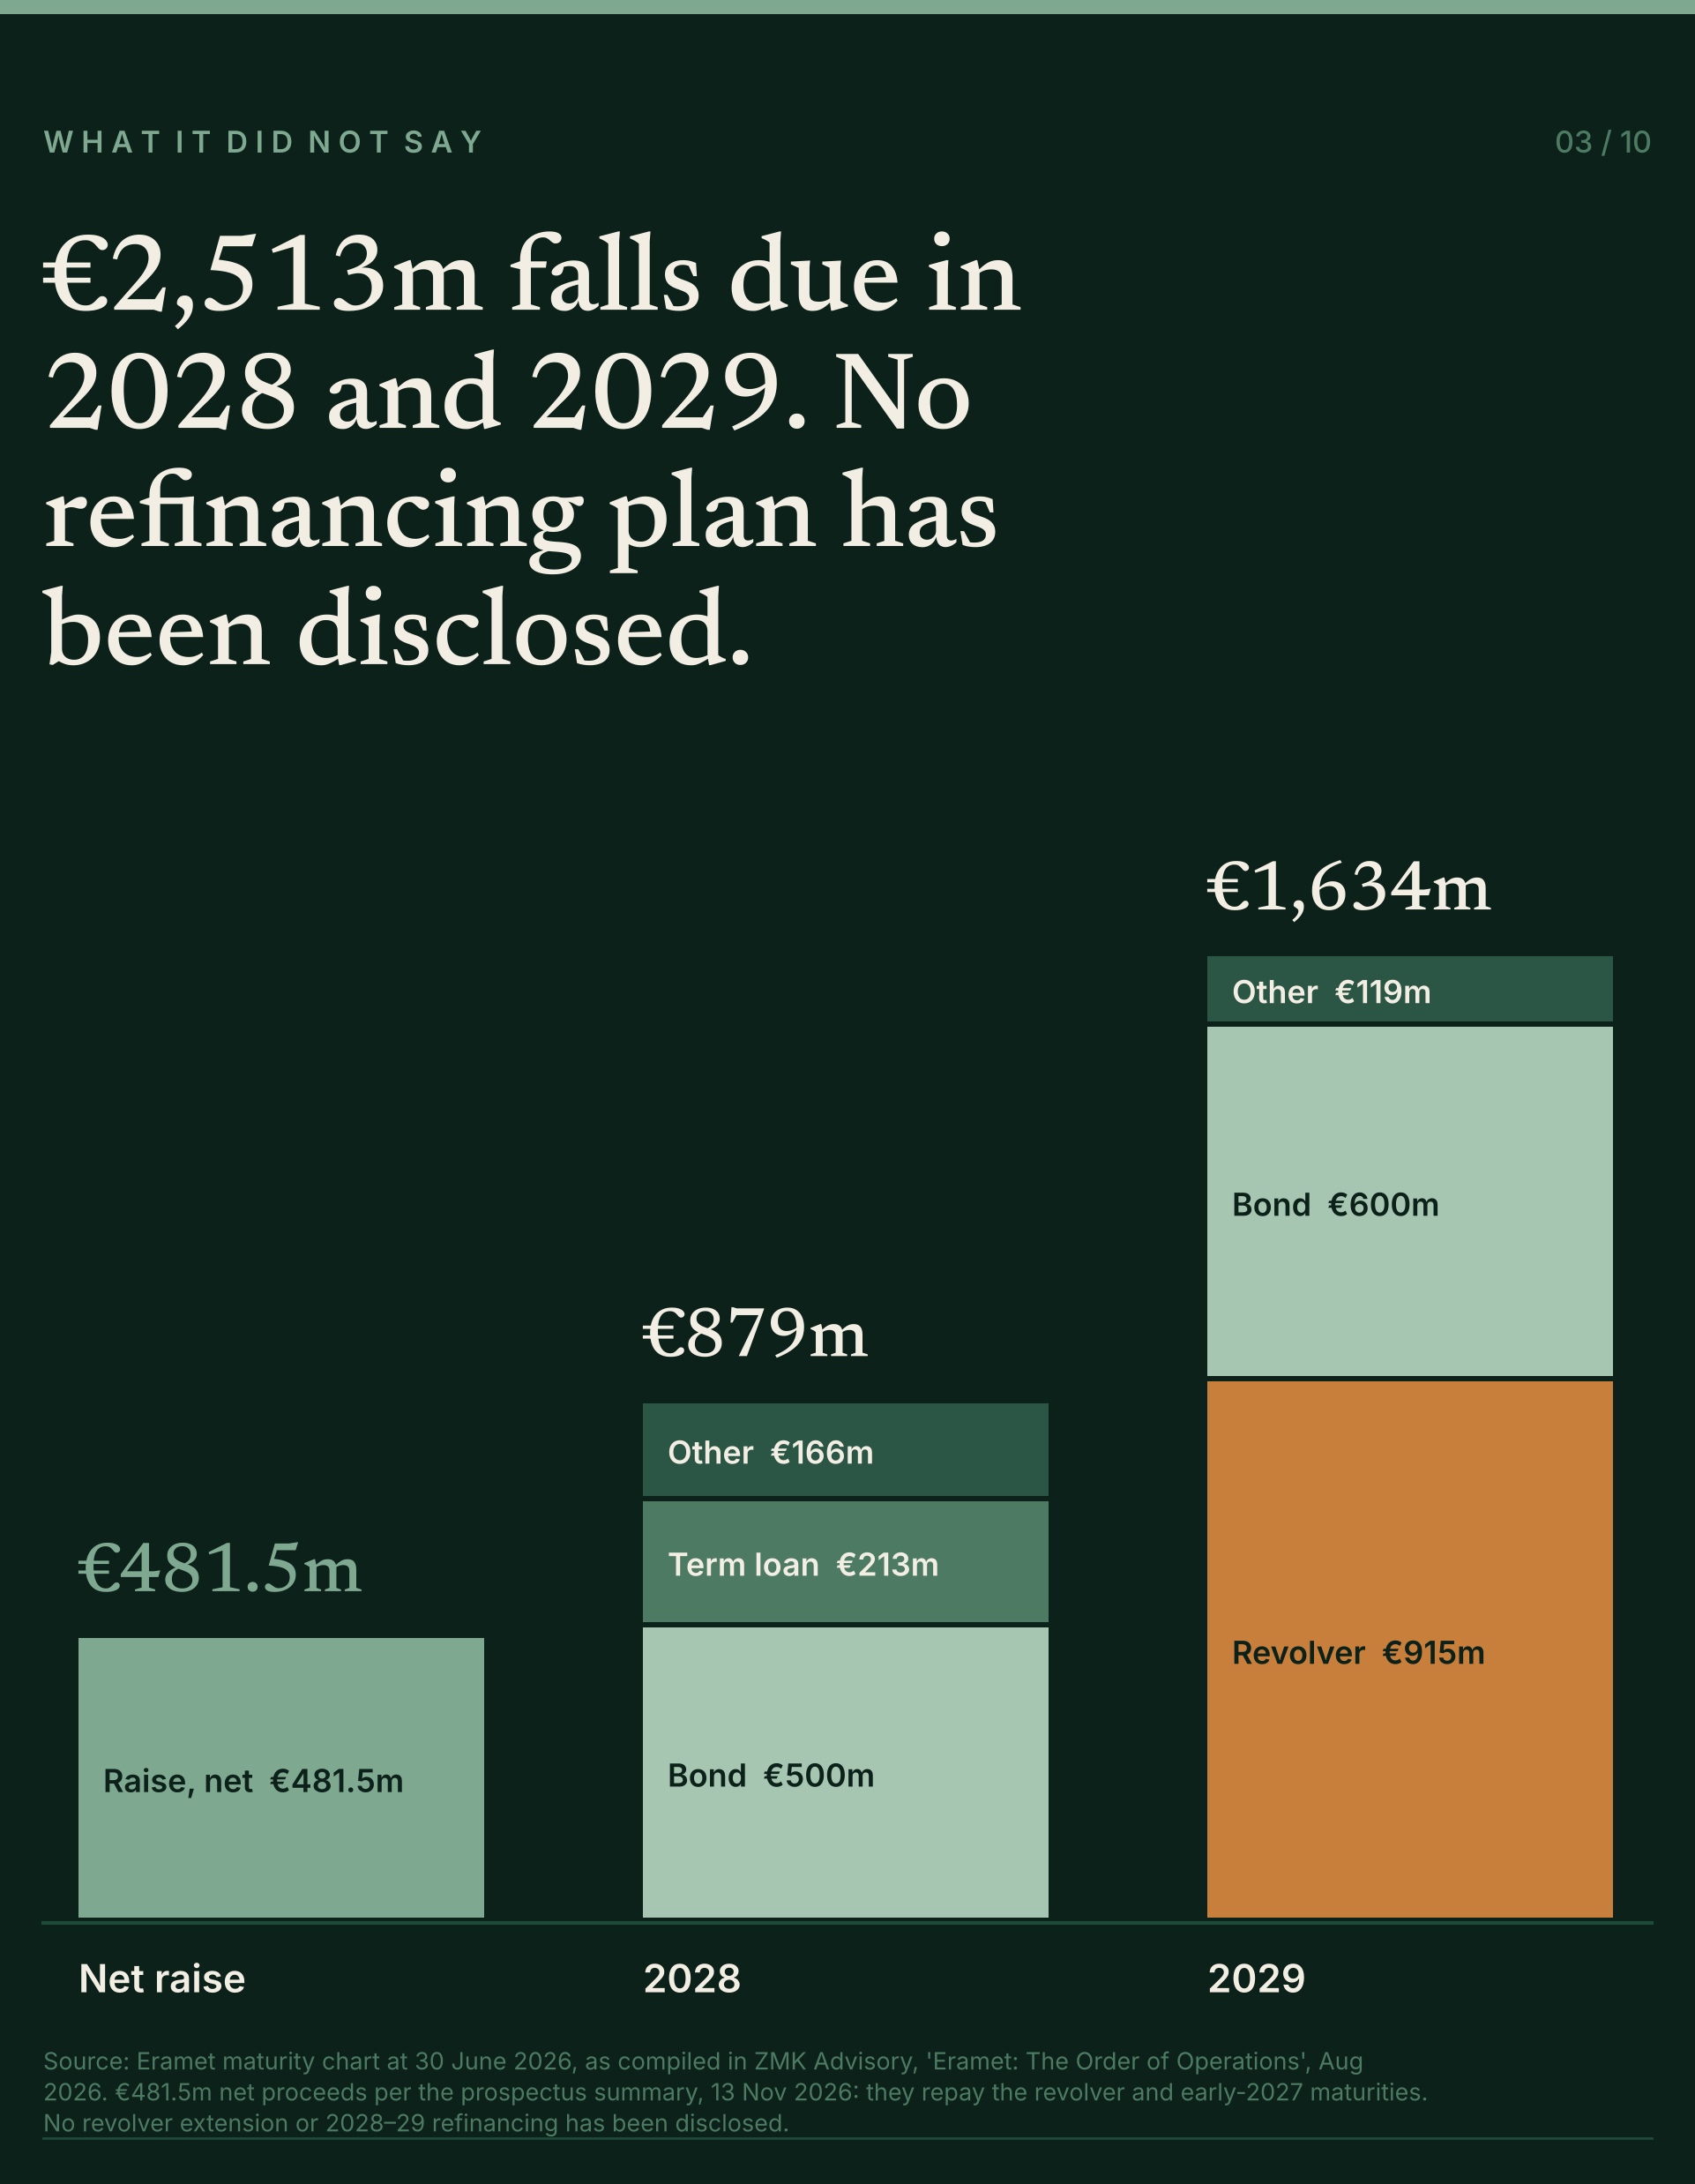
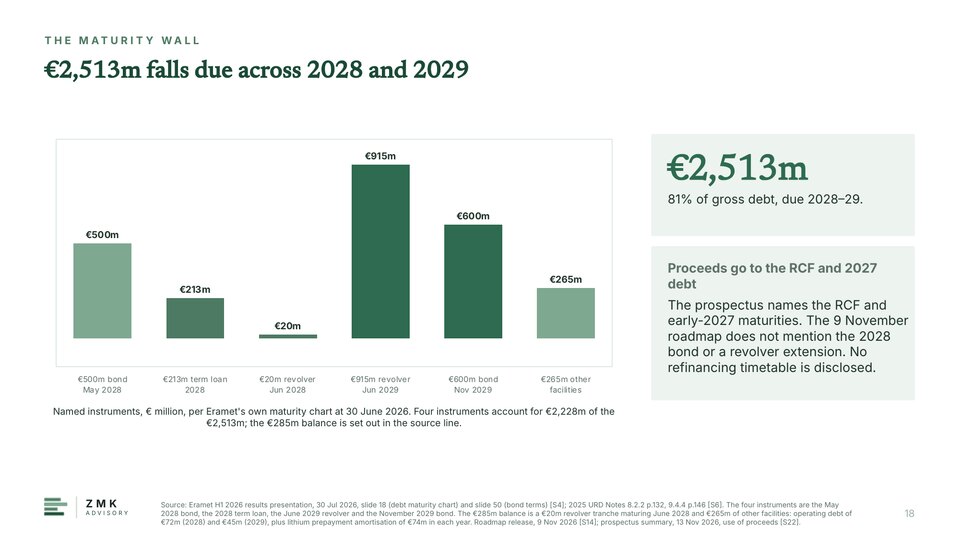
€2,513m falls due in 2028 and 2029, 81% of Eramet's gross debt at 30 June 2026.45 The rights issue raises €500m, about €481.5m net, or 19% of that wall. The prospectus says the proceeds will reduce debt, notably the revolving credit facility and debt falling due in early 2027.16 Eramet itself said on 12 October that failing to complete the raise by mid-2027 would "significantly complicate the necessary refinancing" of debt maturing in the short term.2
The 9 November roadmap sets 2027 volume targets, capex of €280m to €320m, a lithium growth path and a manganese processing plan.1 It does not mention the 2028 bond or the 2029 revolver. The prospectus of 12 November does set out the covenant: gearing of 100% at 30 June 2027, under the revolver and the term loan. Without the raise and a new waiver, Eramet estimates that its working capital could fall up to €500m short by July 2027.16 Three months after Eighty-Three Days, the raise is launched and underwritten. The sequence behind it is not.
What moved since 7 August
| What we flagged | What Eramet has said since | Status |
|---|---|---|
| No backstop for the €500m5 | State subscribes its 27.1% and buys Sorame-CEIR's rights; undertakings signed 23 October; AMF waiver 26 October23; launched 13 November with the balance underwritten by a bank syndicate; settles 4 December15 | Resolved |
| 2027 covenant level undisclosed | Prospectus, 12 November: gearing of 100% at 30 June 2027 under the revolver and term loan; Eramet expects the raise to meet it16 | Resolved |
| €2,513m due 2028–29; revolver fully drawn | No refinancing step disclosed; Eramet calls the refinancing "necessary"2 | Open |
| No permanent chief executive | Christel Bories interim since 1 February; roles to separate once a successor is named12 | Not done |
| Monetisation deadline with no price | Arizaro sale agreed at $71m gross; Centenario and Weda Bay processes, no proceeds in 20261 | Confirmed |
| Weda Bay idle on a 12 Mwmt quota | Restarted in September; quota revised up; 2026 external sales guidance 23–26 Mwmt, from 93 | Overtaken |
| Centenario at 90% of nameplate | At nameplate through October; cash cost below $6,000/t-LCE1 | Overtaken |
The raise: funded, and a change of control
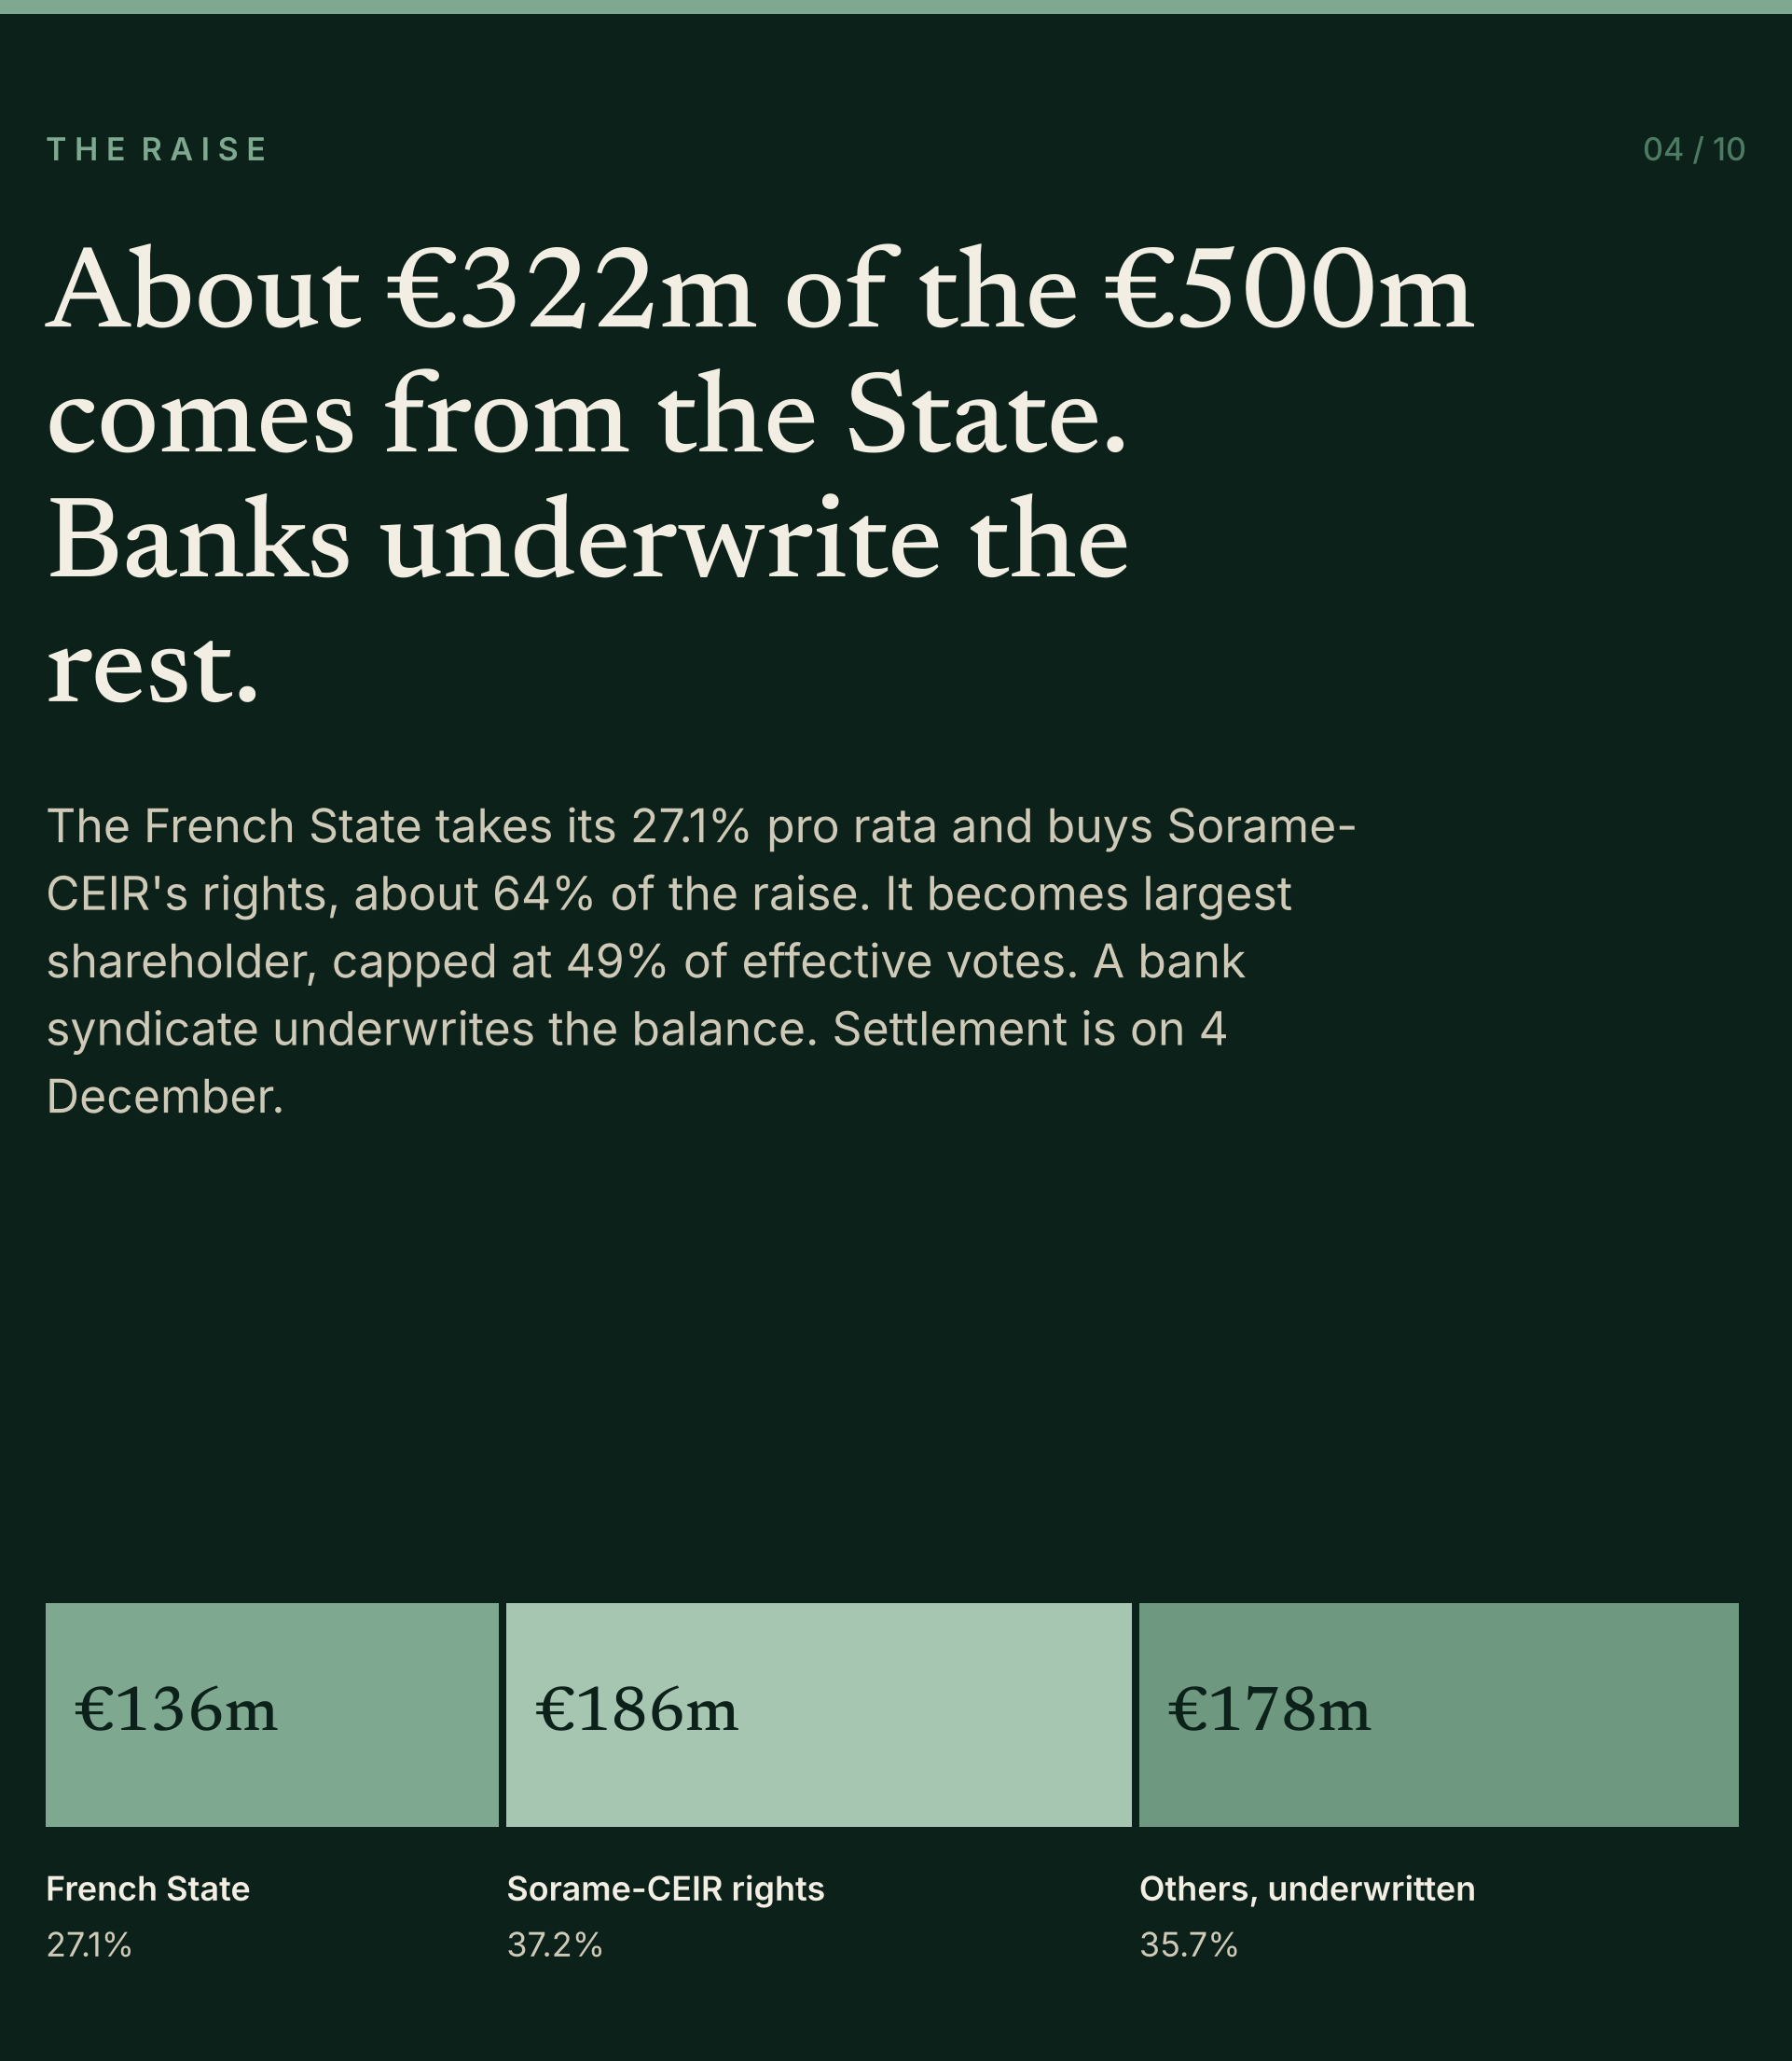
The French State subscribes its 27.1% pro rata and buys Sorame-CEIR's preferential rights at a 5% discount, up to the point where it holds 49% of effective voting rights. Put and call options with Sorame-CEIR keep the State at or below 50% of capital. Sorame-CEIR converts to bearer shares and caps itself at 30% of effective votes. Eramet will pay no dividend until adjusted leverage is below 1.0x.2
The rights issue launched on 13 November: 34,506,054 new shares at €14.49, six for every five held. The State commits about €322m, some 64% of the raise; Sorame-CEIR subscribes for nothing; and a bank syndicate underwrites the balance of about €178m. Results are due on 2 December and settlement on 4 December.15 On end-2025 holdings, the State's €322m splits into about €136m for its own 27.1% and €186m for Sorame-CEIR's 37.2% (our arithmetic). Until settlement the change of control is conditional. The shares closed at €37.24 the day after the State investment was announced, against €43.70 the previous day.14
The wall behind the raise
| Instrument | Due | €m |
|---|---|---|
| Bond | May 2028 | 500 |
| Term loan | 2028 | 213 |
| Other facilities | 2028 | 166 |
| Revolving credit facility, drawn in full | June 2029 | 915 |
| Bond | November 2029 | 600 |
| Other facilities | 2029 | 119 |
| Total, 2028 and 2029 | 2,513 |
Source: Eramet's maturity chart at 30 June 2026, as compiled in our August deck.45 The revolver is 36% of the wall on its own. Extending it needs lender consent and an arrangement fee, and no buyer. In August we set out three steps that take €1,413m off the 2028–29 wall without selling anything: extend the revolver, tender for the 2028 bond before the extension is announced, then apply the balance of the raise to the term loan.5 None is mentioned in the releases since.
Lithium: bought, pre-sold, now offered
| Date | Transaction | Amount |
|---|---|---|
| July 2023 | Glencore prepayment against c.50 kt-LCE over five years, about half of output per Eramet's May 2026 presentation8 | $400m |
| October 2024 | Buys Tsingshan's 49.9% of Eramine, holder of the Centenario and Arizaro concessions79 | $699m net cash |
| October 2026 | Phase 1 brownfield expansion, +11 kt-LCE; investment decision possible by end-20273 | c.$350m |
| November 2026 | Arizaro concessions: sale agreed, one condition outstanding, closing expected by year-end1 | $71m gross |
| November 2026 | Minority stake in Centenario offered to partners1 | Not priced |
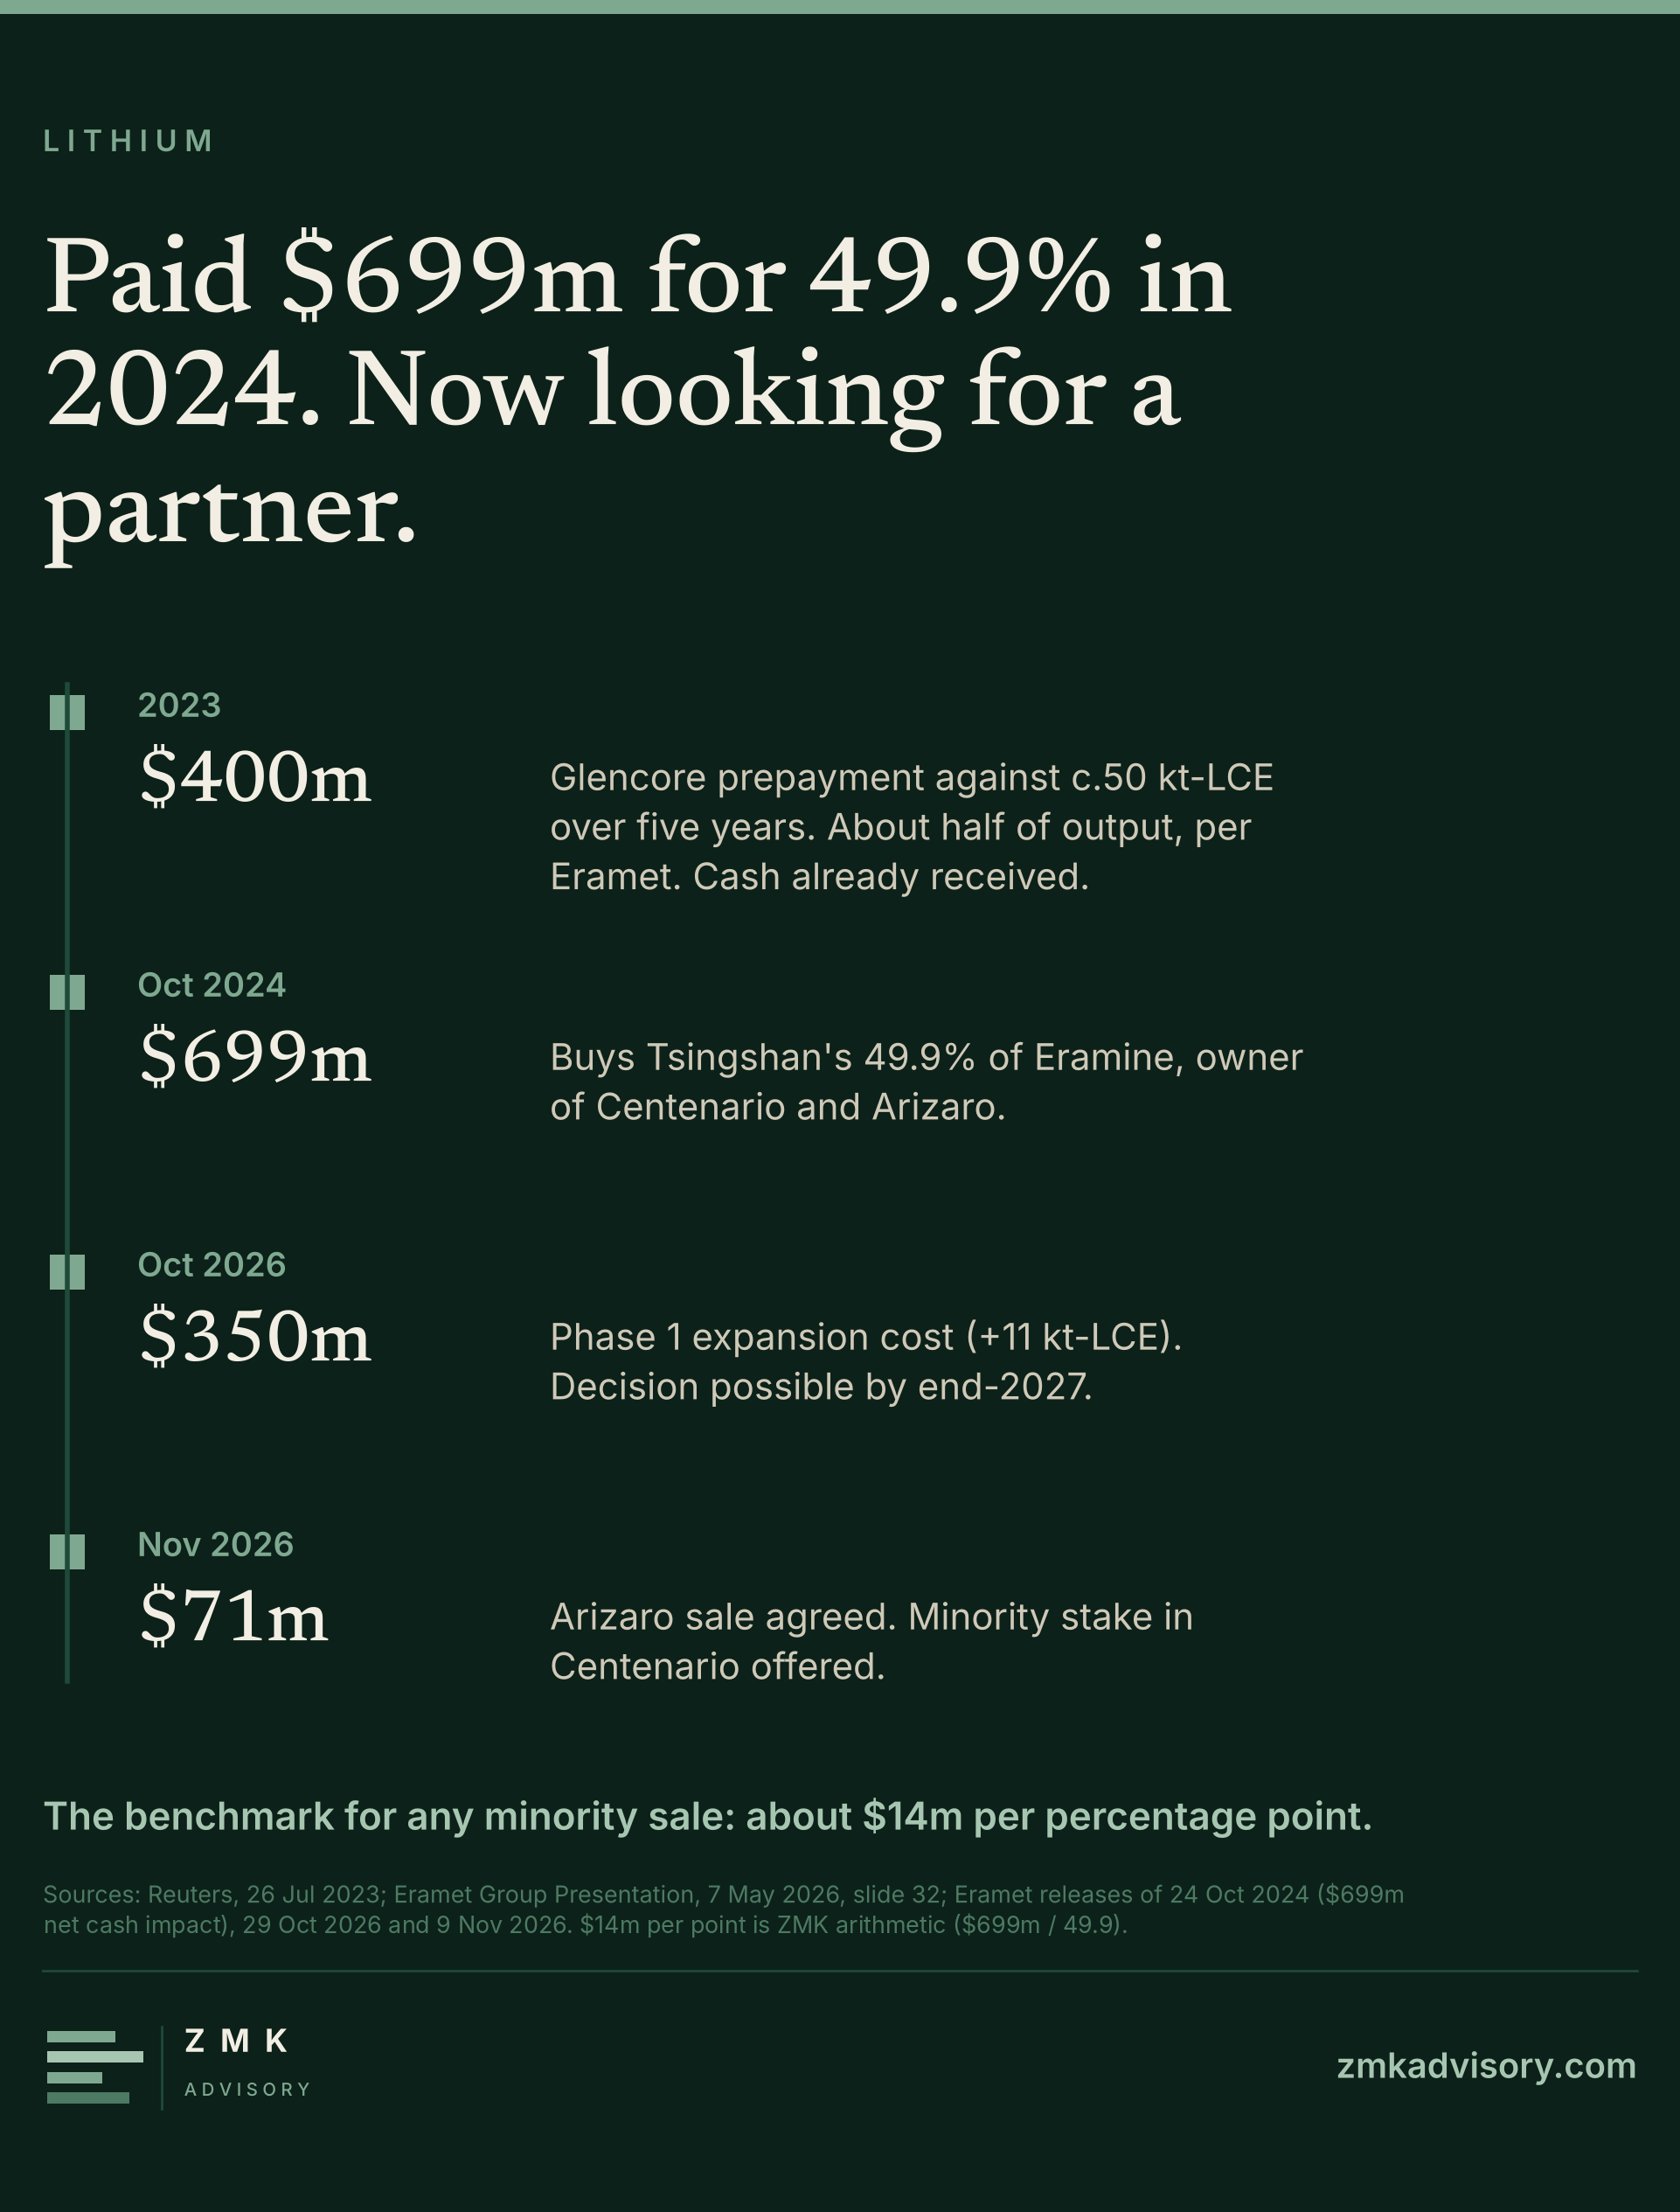
Centenario is the asset that works. It produced at nameplate through October, ahead of target.1 The question is price and timing. Eramet bought out Tsingshan two years ago, saying the timing was right because lithium prices were cyclically low.7 It now seeks a minority partner while assuming about $13,000/t for the fourth quarter, against a nine-month average of $20,389.3 The benchmark is what Eramet itself paid: about $14m per percentage point (our arithmetic).
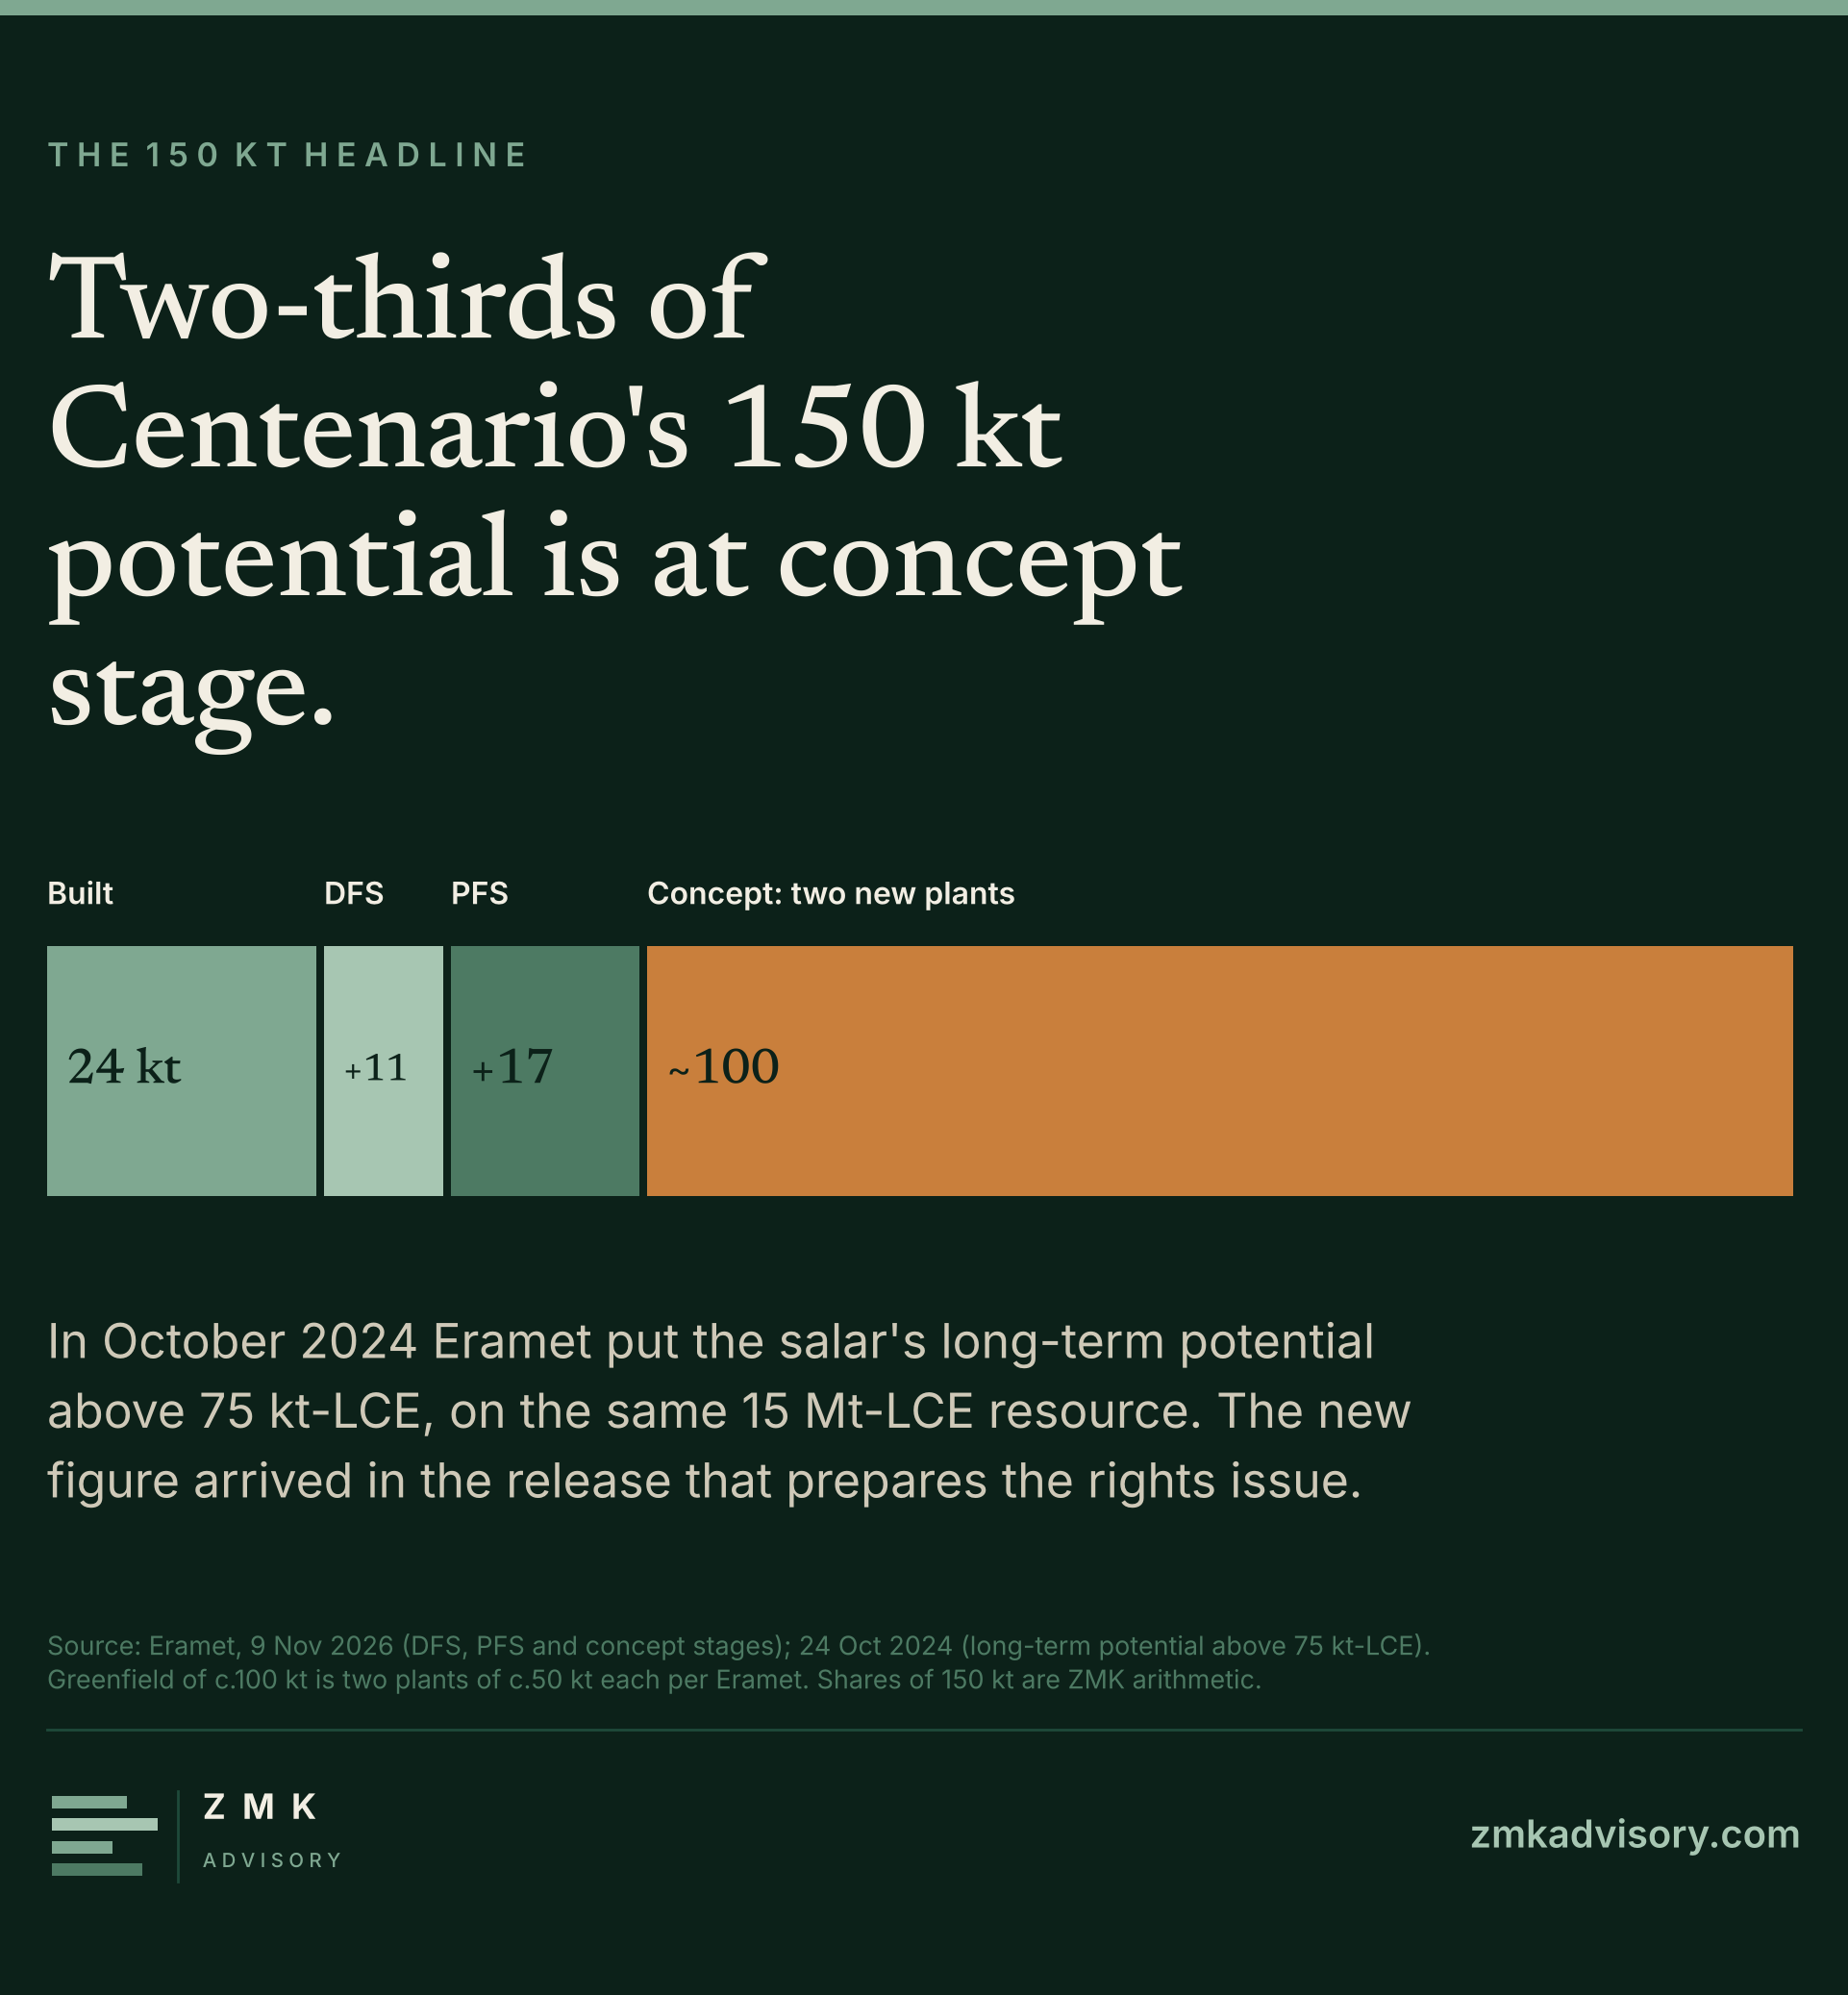
The roadmap lifts the salar's long-term potential to close to 150 kt-LCE a year. 24 kt is built, 11 kt is at detailed feasibility, 17 kt at pre-feasibility, and around 100 kt is two greenfield plants at concept stage.1 In October 2024 Eramet put the long-term potential above 75 kt on the same resource.7
Weda Bay: we revise our threshold
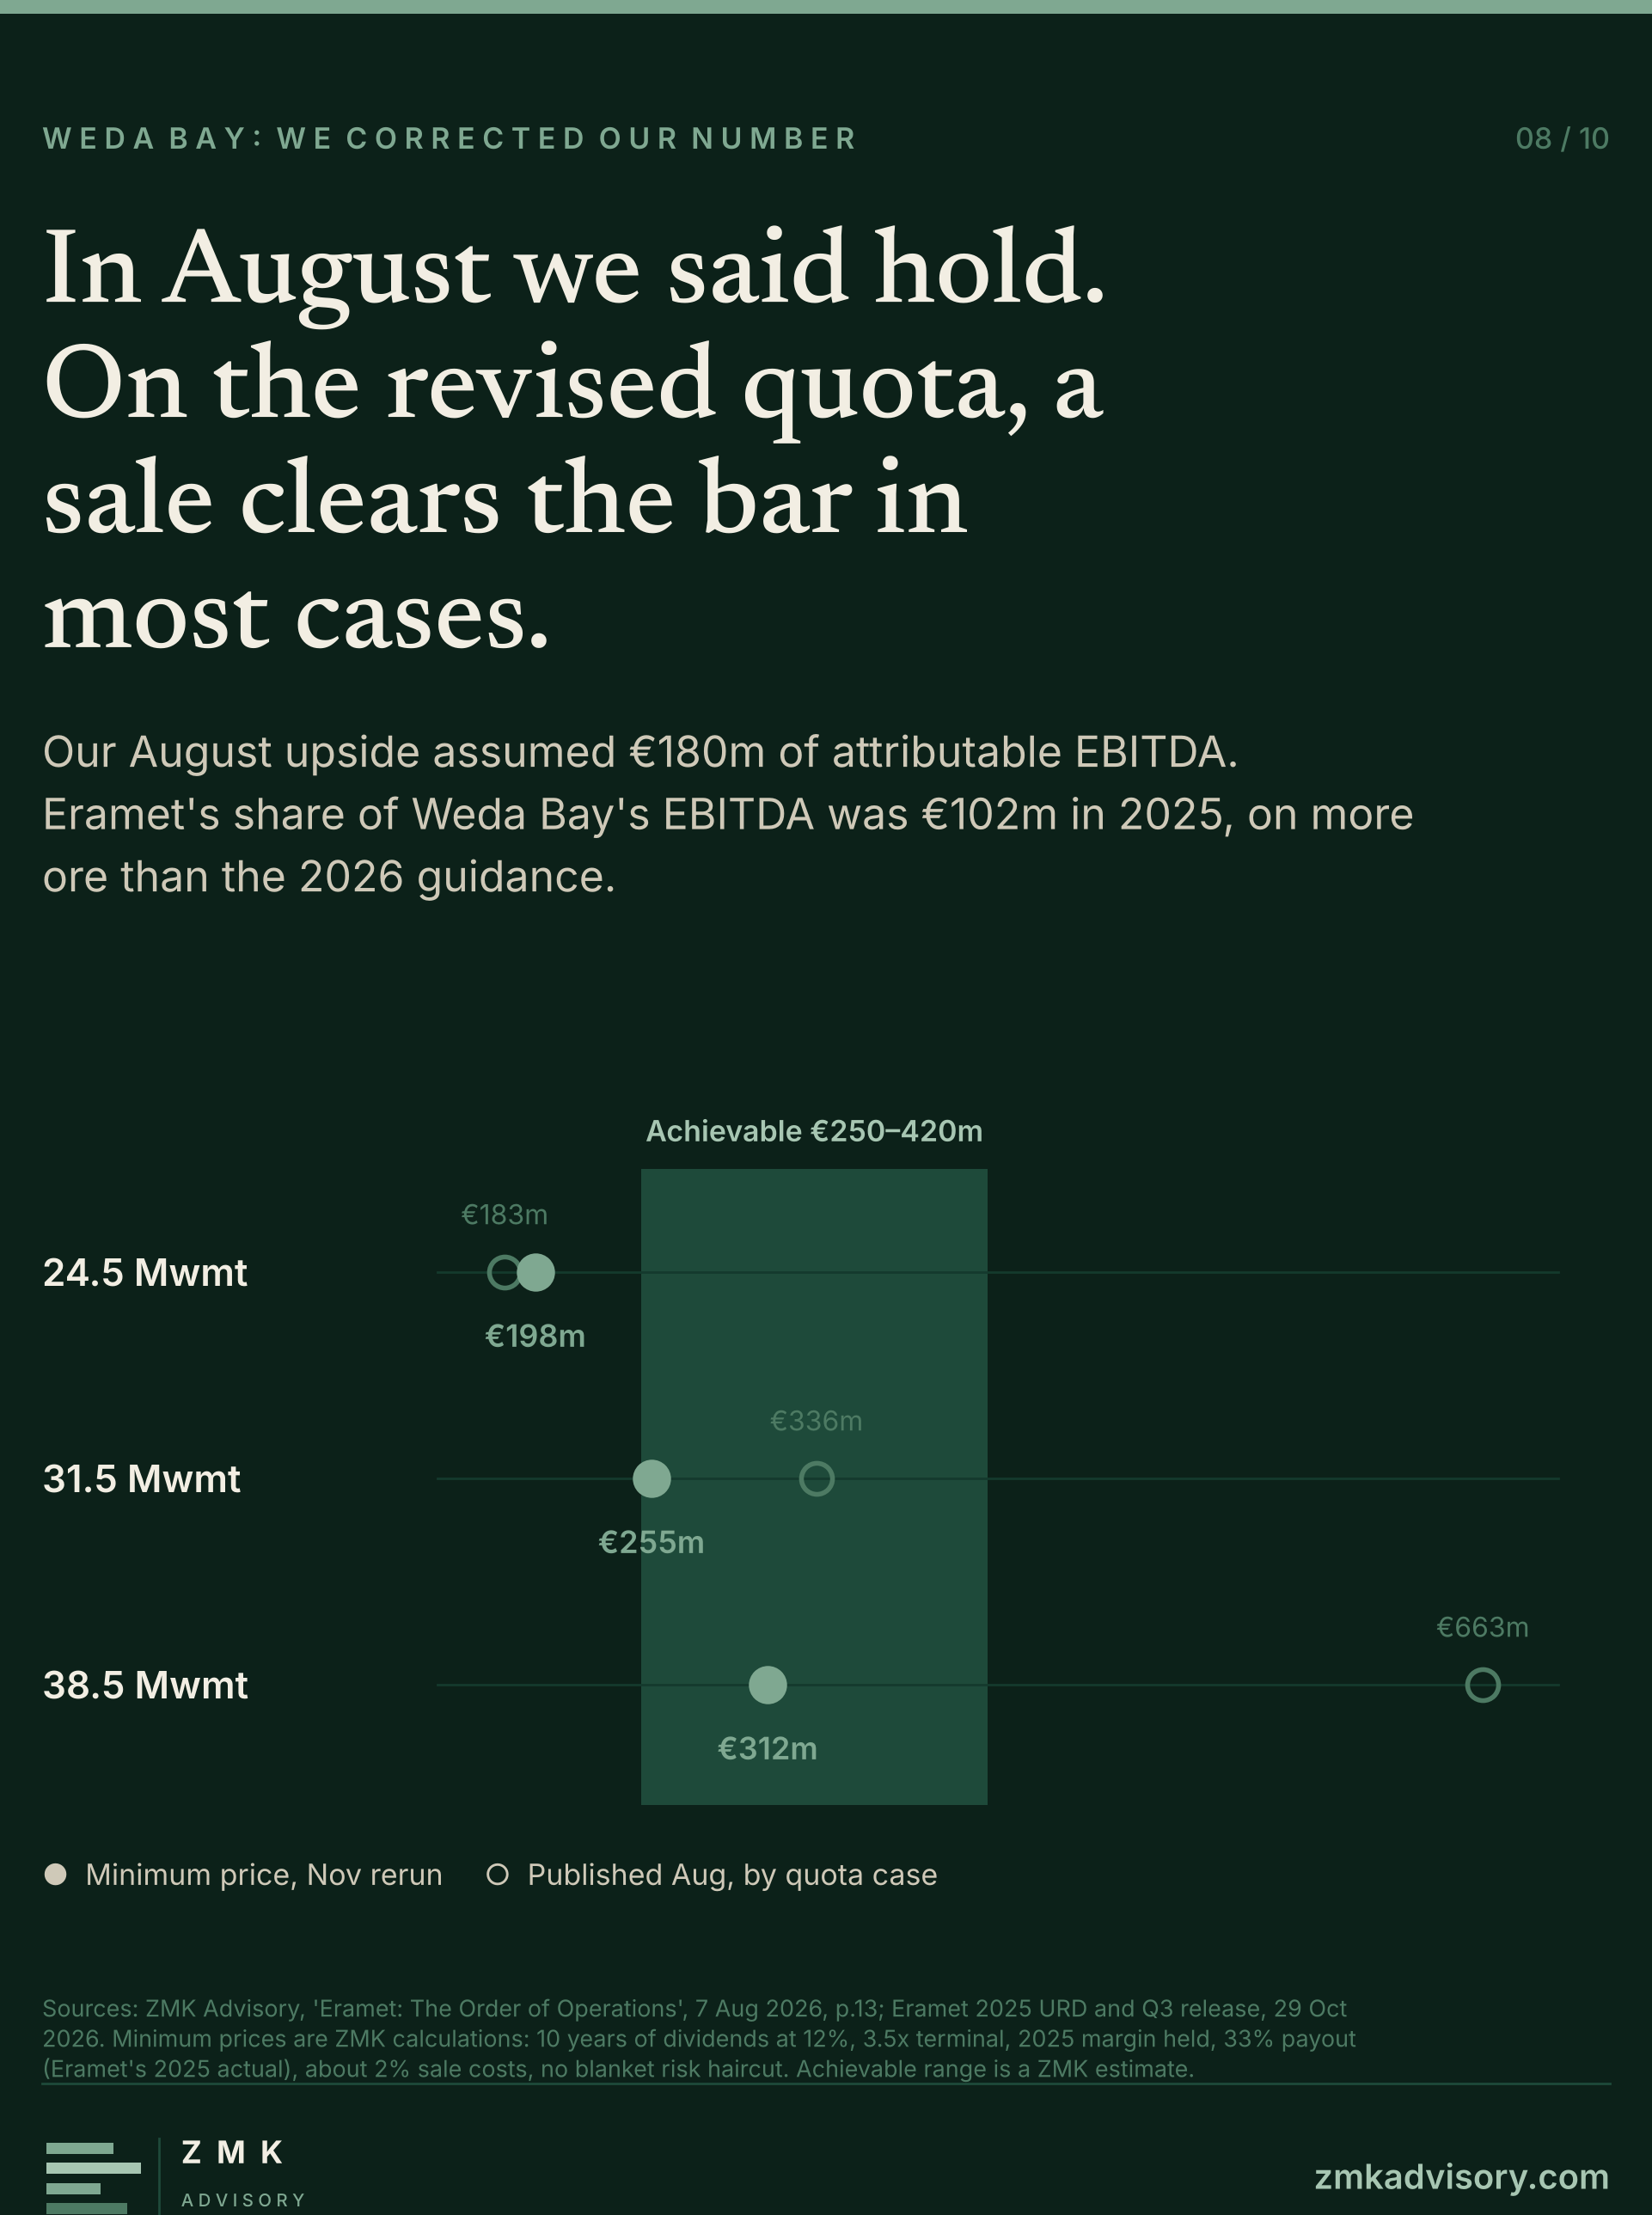
In August we set the price below which Eramet should keep its 38.7% of PT Weda Bay Nickel at €183m, €336m or €663m, depending on Indonesia's quota decision.5 The €663m case, if the July quota revision was granted, assumed €180m of attributable EBITDA and a €100m dividend. Eramet's share of Weda Bay's EBITDA was €102m in 2025, on 38.5 Mwmt of external ore sales.63 A revision was granted in September and 2026 external sales guidance rose to 23–26 Mwmt, from 9.3 Our upside rested on earnings the asset has not shown, so we have rerun it.
| 2027 volume case | Attributable EBITDA | Minimum price, Nov | Published, Aug, by quota case |
|---|---|---|---|
| 24.5 Mwmt: 2026 guidance midpoint repeated | €65m | €198m | €183m |
| 31.5 Mwmt: average of 2025 and 2026 | €84m | €255m | €336m |
| 38.5 Mwmt: 2025 repeated | €102m | €312m | €663m |
Method: as in August, ten years of dividends at 12% and a 3.5x terminal multiple on attributable EBITDA, plus about 2% for sale costs, with no blanket risk haircut. The August dividends were set case by case; here they are 33% of attributable EBITDA throughout, the share Eramet actually received in 2025. The August rows were quota cases and are shown for reference, not as like-for-like scenarios. Assumptions, ours: Eramet's 2025 margin of €6.86/wmt on a 100% basis held flat, 33% of attributable EBITDA paid as dividends, €/$1.15. A $5/wmt move in price on all volume shifts the minimum by about €120m to €195m across the cases, so the price deck matters as much as the quota. The 2027 quota is not yet granted, and Eramet guides external sales "in line with the previous two years, subject to obtaining permits".1
SLN: the State on both sides
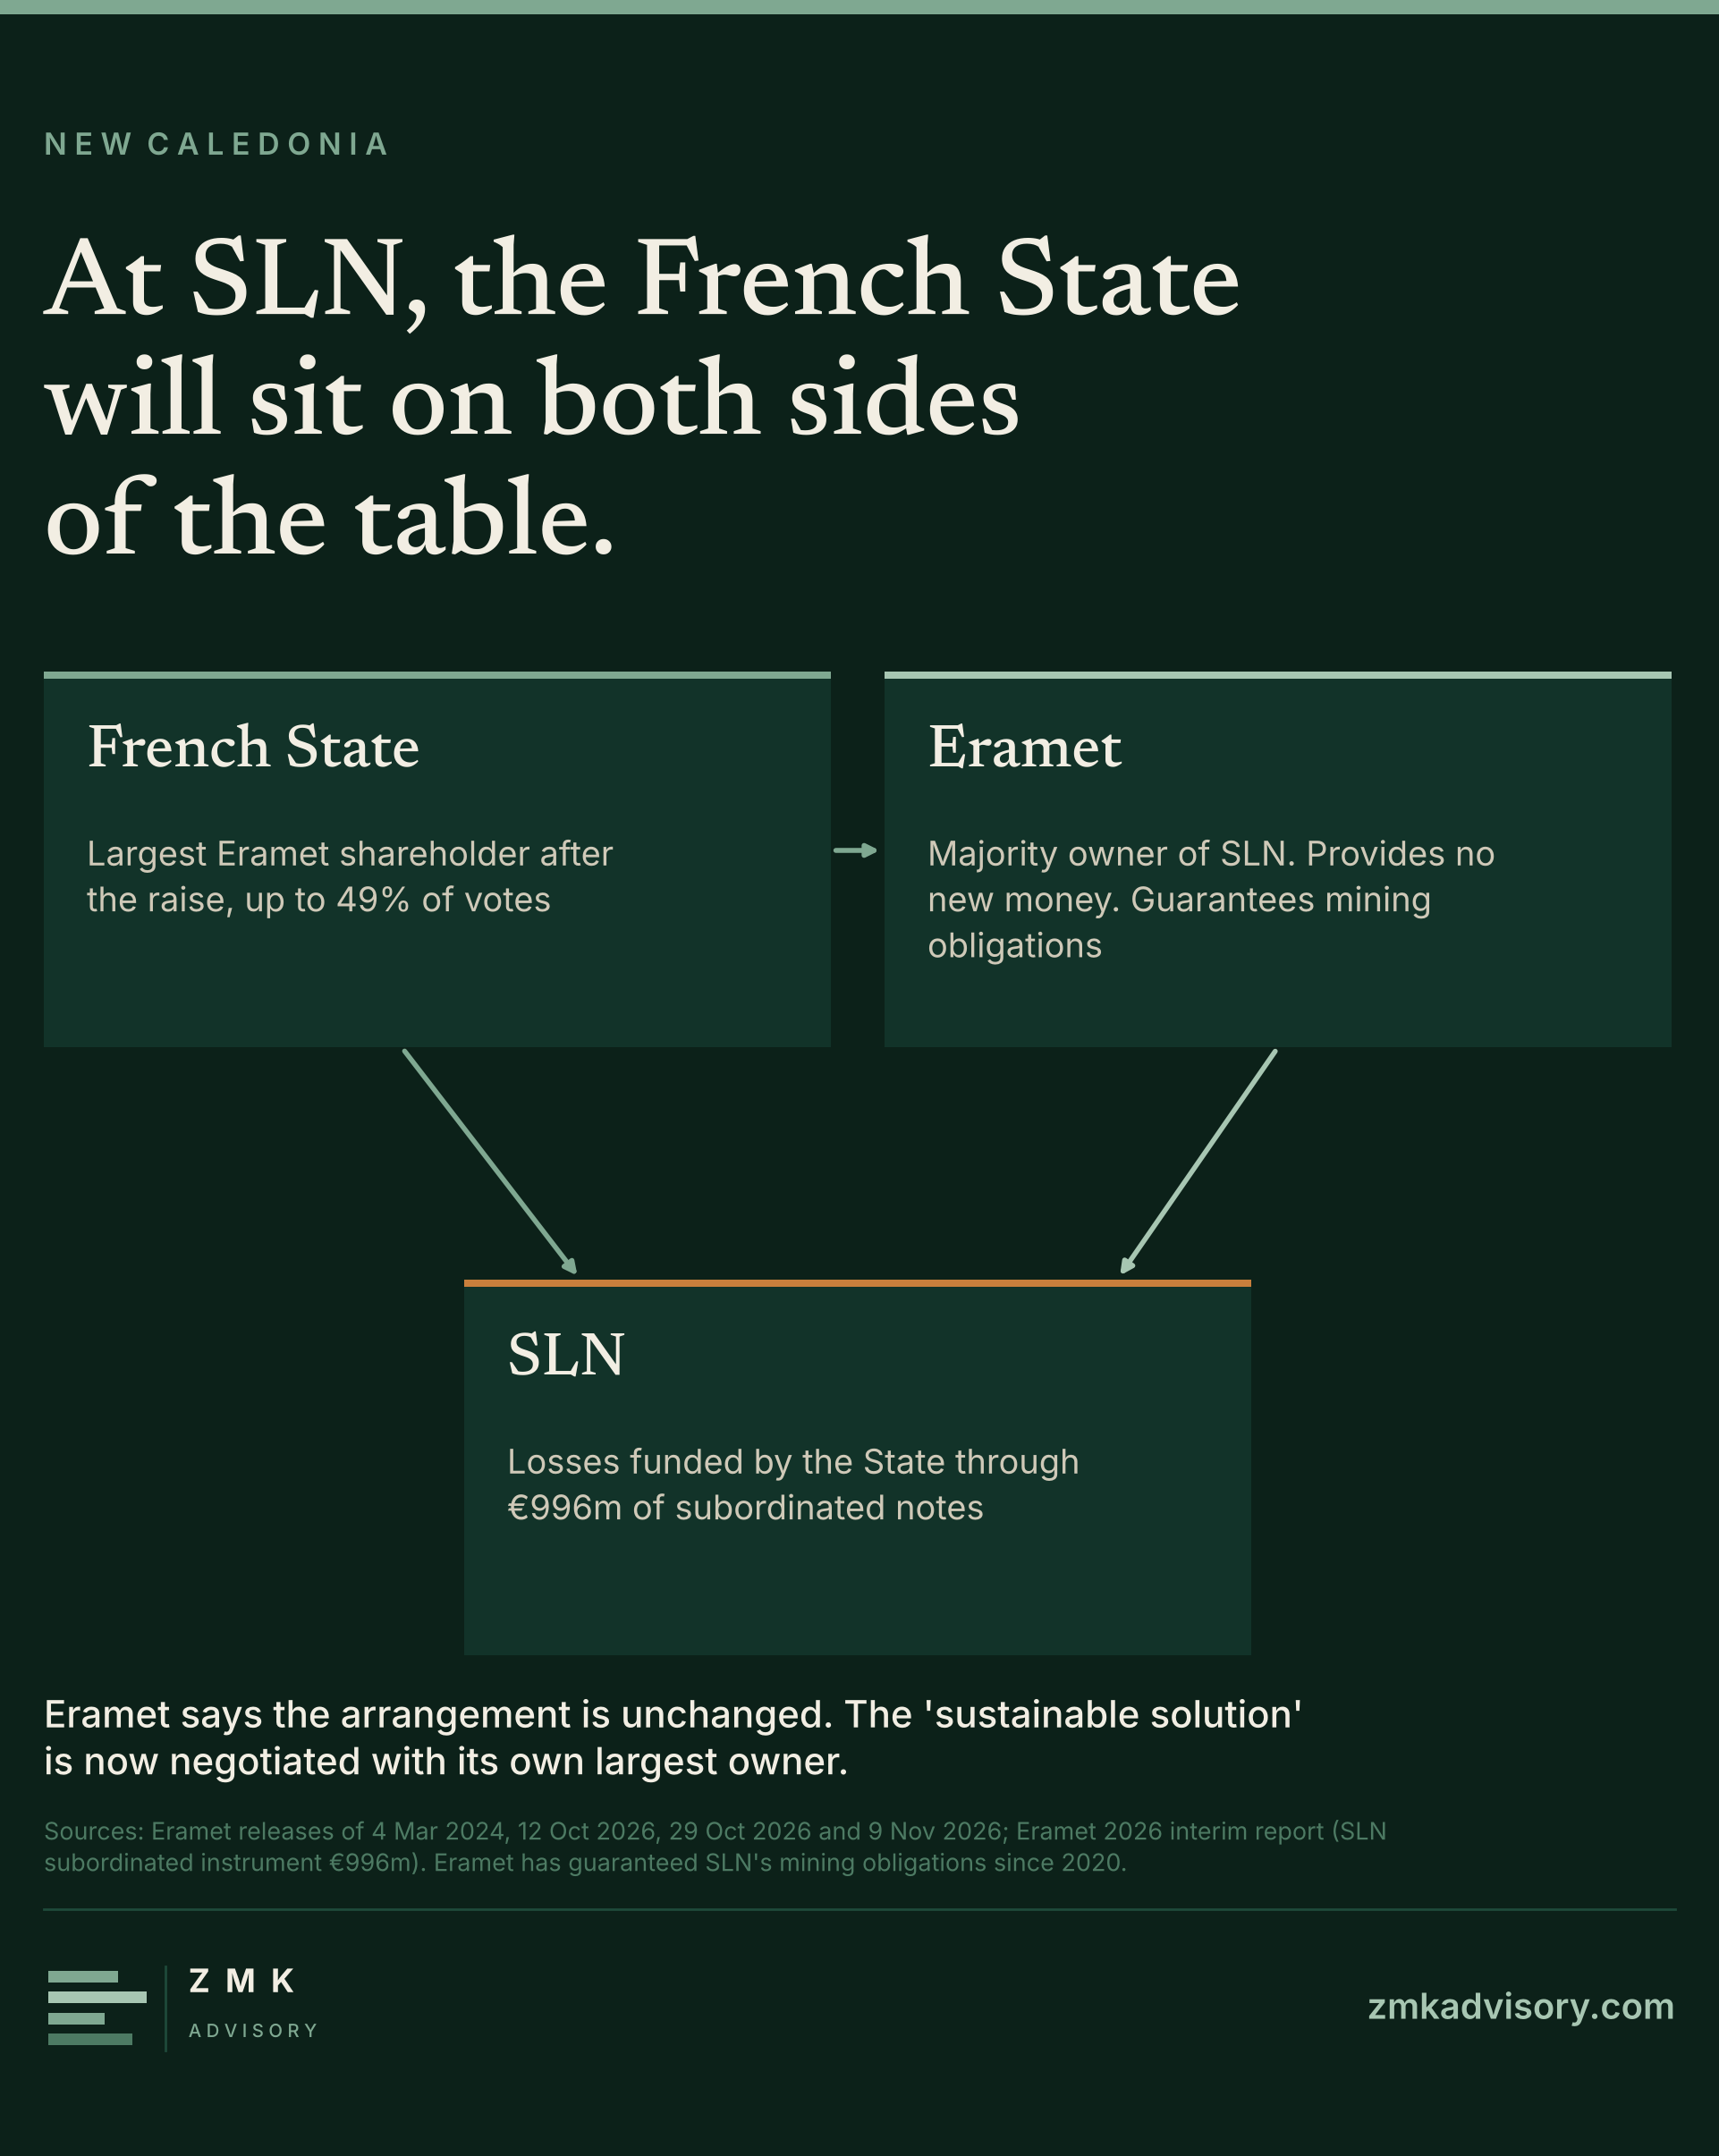
Eramet is SLN's majority owner and has provided no new financing since March 2024. That month the State converted €320m of loans into quasi-equity and Eramet converted €325m of intra-group loans on the same terms; and it has since funded SLN's losses through undated subordinated notes: €996m at 30 June 2026.104 Eramet's adjusted EBITDA, leverage and capex exclude SLN or are stated net of the State's contribution.1 Eramet still provides guarantees for SLN's mining obligations, as it has since 2020.11
The roadmap says the agreement with the State is unchanged and the objective remains a sustainable solution with no impact on the group's balance sheet.1 After the raise the State is Eramet's largest shareholder. Any SLN solution is then negotiated between Eramet and its largest owner.
Three more facts from the record
- Inventory. An independent count in September found counting errors in manganese ore stockpiles: €39m restated to equity at 1 January 2025 and €20m charged to 2026 EBITDA, offset by a €20m provision reversal.3
- Leadership. Christel Bories has been interim chief executive since 1 February, 285 days. The board said the chair and chief executive roles would be separated again once a successor was named.12
- Gabon. The planned manganese oxide plant, about $40m for 60 kt a year, would process about 90 kt of ore, about 1.3% of the 6.8 to 7.3 Mt Eramet plans to transport in 2027 (our arithmetic). Gabon has announced a ban on raw ore exports from 1 January 2029.113
The sequence, updated
| When | Step | Needs | Owner |
|---|---|---|---|
| Now | Name a permanent chief executive and complete the separation the board resolved on in January 2025 | Nothing external | Board |
| Before June 2027 | Agree extension of the €915m revolver; tender for the May 2028 bond only on executable terms | Lender consent | CFO |
| Q4 2026 | Settle the €500m rights issue, 4 December | Underwritten; launched 13 November | Board |
| 2027 | Sell Weda Bay only at or above the rerun minimum for the quota granted | Buyer, Tsingshan, Indonesia | CEO |
| 2027 | Centenario partner only at $14m per point or better, funding its share of Phase 1 | Partner | CEO |
| 2027 | SLN transfer to a State vehicle, on terms set by independent directors | State, EU rules | Independent committee |
Every step is ours, built from Eramet's own disclosures. The first two need no buyer and no new capital. They are also the two that the roadmap does not mention.
- If a covenant test is missed, will lenders waive it, and how does SLN's State quasi-equity count?
- Has the extension of the €915m revolver, due June 2029, been sought?
- When will a permanent chief executive be named?
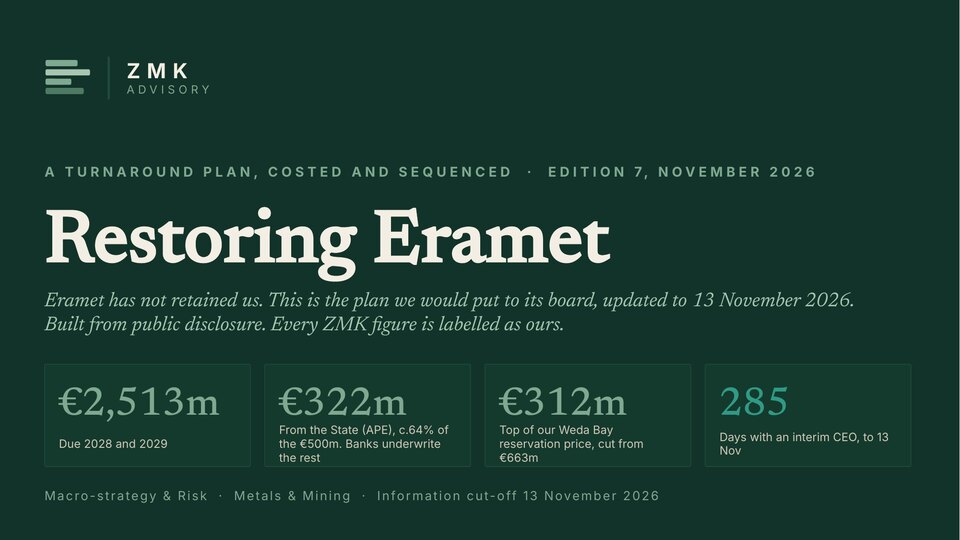
Restoring Eramet: the turnaround plan, costed and sequenced.
Fifty pages behind this note and the film: the model, the refinancing waterfall, the options for each asset and the board resolutions, in the order they have to happen. Every figure is traced to a named, dated filing, and every ZMK estimate is labelled as ours.
- p. 26How much of the €2,513m can be moved without new money, and how much is left.
- p. 31The price below which Weda Bay should be kept, rerun for November.
- p. 34Five routes for SLN, ranked by what each costs Eramet.
- pp. 40–41What the equity is worth on our model, and the bridge from EBITDA.
- p. 43The board resolutions: four to approve, four to negotiate, two to commission.
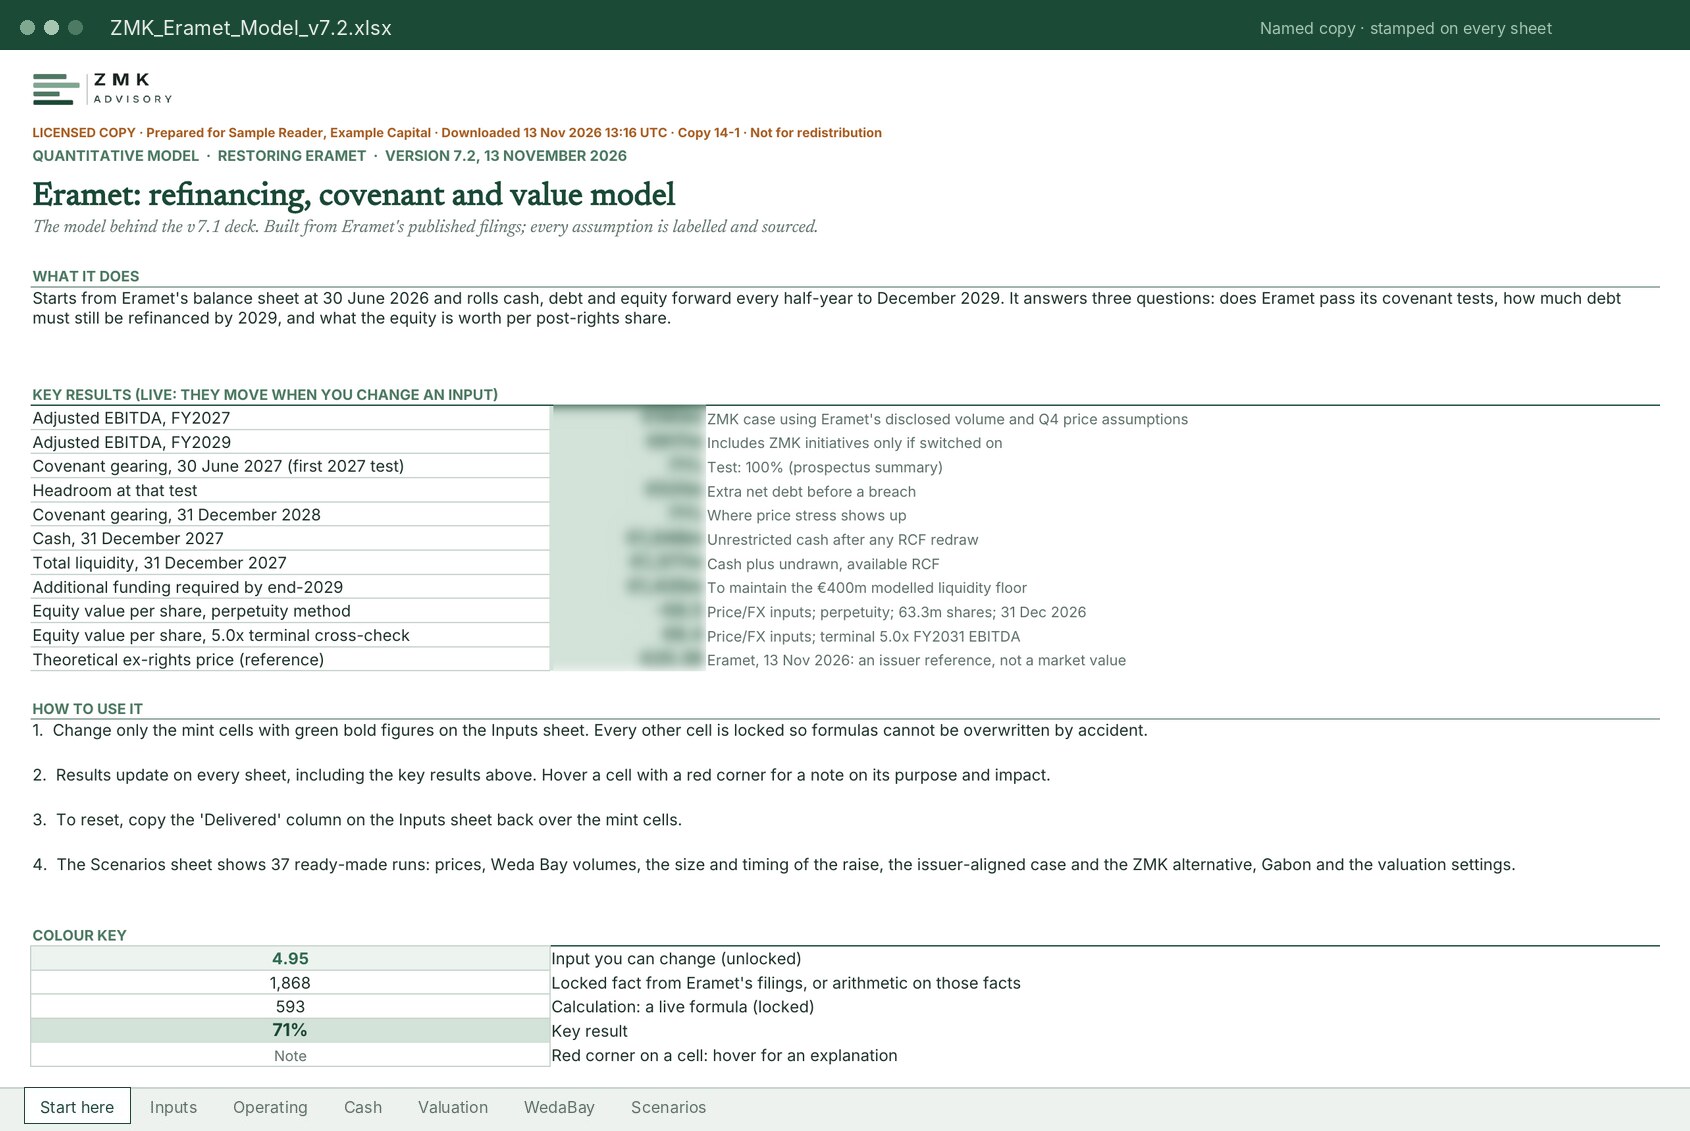
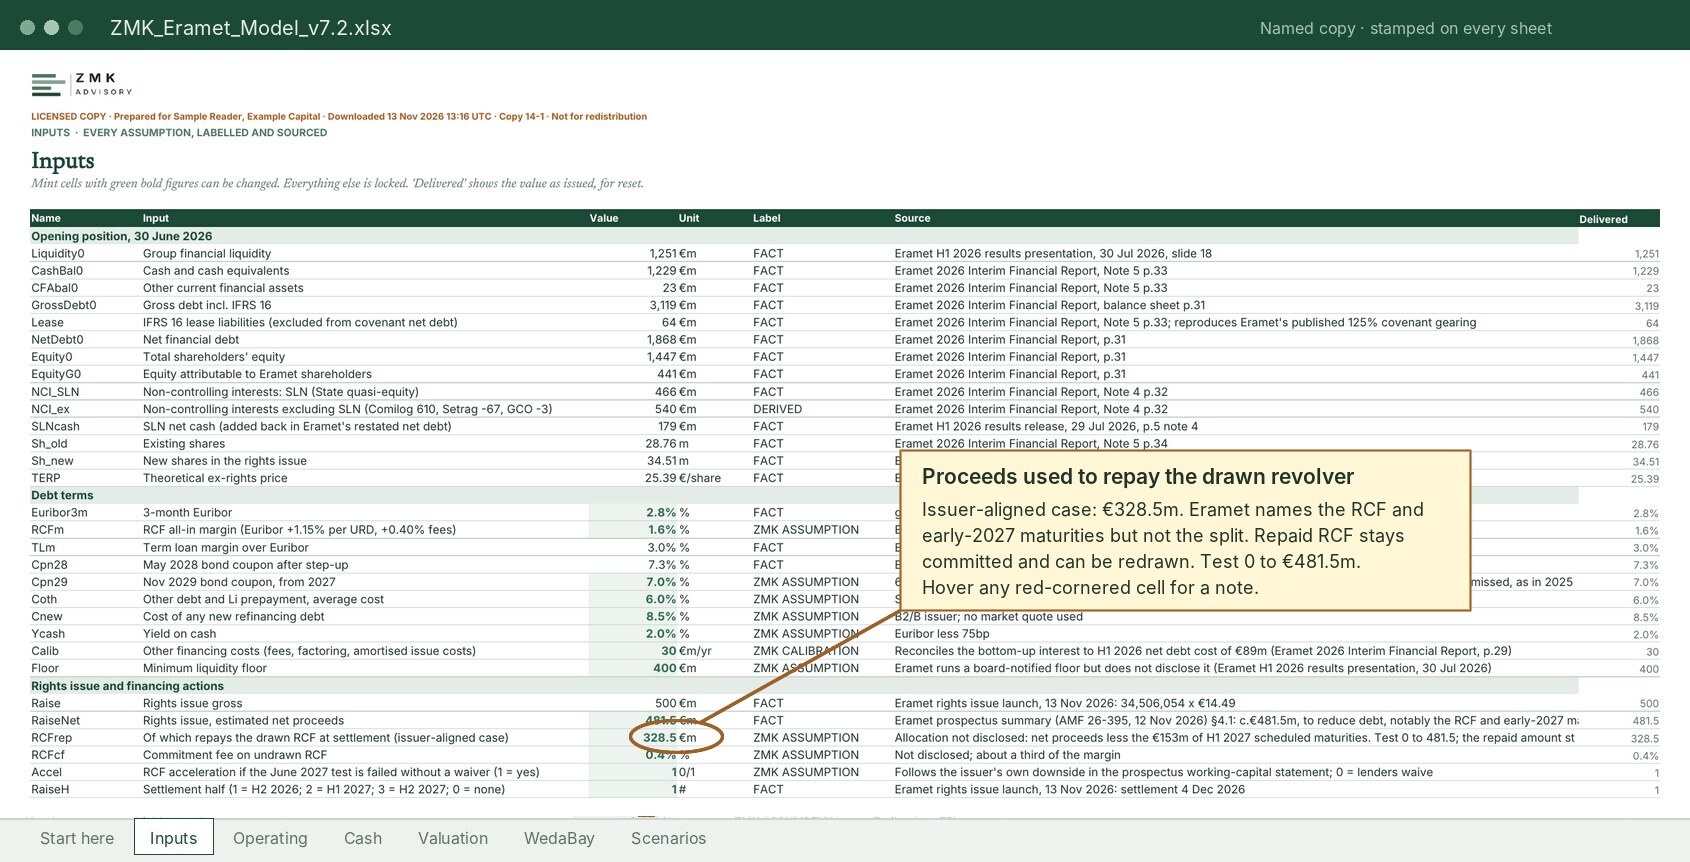
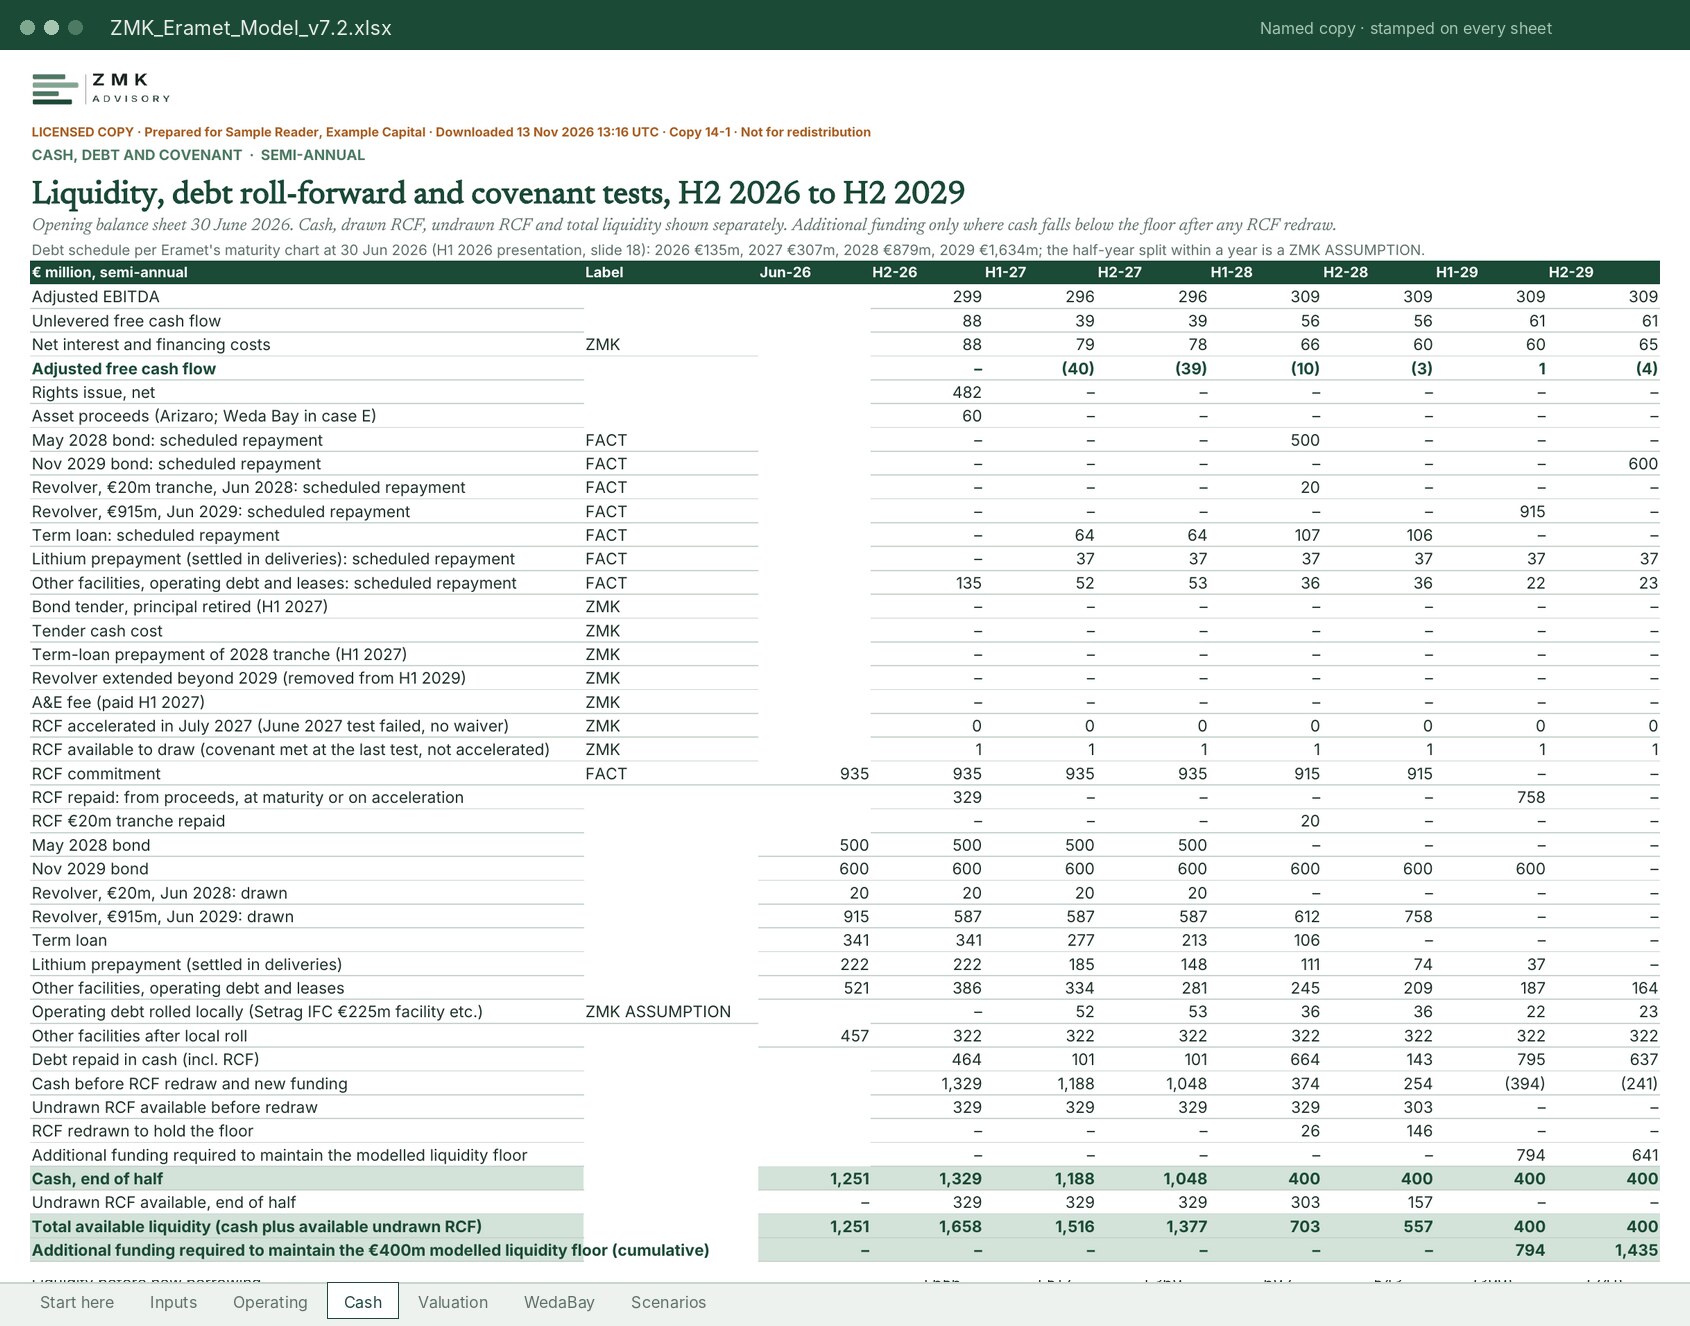
Every number in the deck, recomputed in one workbook.
Start from Eramet’s balance sheet at 30 June 2026 and roll cash, debt and equity forward every half-year to 2029. Change the manganese price, the Weda Bay quota or the revolver extension, and the June 2027 covenant test and the 2029 refinancing need move with it. Every input says whether it is Eramet’s figure or ours, and where it comes from.
A principal will take you through the deck in thirty minutes, on the questions that matter to your side: lenders, shareholders, the State or a counterparty in a sale process.
Every Field Note goes live on this site first, then on LinkedIn and X.
Follow ZMK Advisory to see the next one on the day it publishes.
- Eramet, "Eramet outlines its short- and medium-term operational and strategic roadmap", 9 November 2026. Link
- Eramet, "Eramet confirms its 2026 capital increase project, backed by the support of its reference shareholders and by a strategic investment by the French State", 12 October 2026. Link
- Eramet, "Eramet: solid operational momentum in Q3 and progress on the funding plan", 29 October 2026. Subscription undertakings, AMF waiver, RKAB revision, inventory recount, Q4 price assumptions, Appendix 3 volumes. Link
- Eramet, 2026 Interim Financial Report, 29 July 2026. Debt maturity schedule at 30 June 2026; SLN subordinated instrument of €996m. Link
- ZMK Advisory, Eighty-Three Days, and Eramet: The Order of Operations (17 pages), 7 August 2026. Holdings at end-2025, maturity compilation, Weda Bay thresholds. Link
- Eramet, 2025 Universal Registration Document, Notes 11.5.1 to 11.5.2: PT Weda Bay Nickel carrying value €367m, 100% EBITDA €264m, Eramet share €102m at 38.7%, dividends €34m in 2025.
- Eramet, "Eramet regains full ownership in its flagship lithium business in Argentina", 24 October 2024. Link
- Reuters, "Eramet says it secured $400 mln lithium deal with Glencore", 26 July 2023, carried by Mining Weekly; share of output from Eramet Group Presentation, 7 May 2026, slide 32. Link
- Marval O'Farrell Mairal, counsel to Tsingshan, on the sale of its stake in Eramine (Centenario and Arizaro concessions), 22 October 2024. Link
- Eramet, "SLN's debt conversion to strengthen Eramet Group's balance sheet", 4 March 2024. Link
- Eramet, agreement with the French State to extend financial guarantees granted to SLN, reported by MarketScreener. Link
- Eramet, "Announcement from the Board of Directors regarding the management of the Group", 1 February 2026. Link
- Eramet, "Eramet's response to the Gabonese government's announcement on crude manganese export ban starting in 2029", 2 June 2025. Link
- Les Nouvelles Calédoniennes (AFP), share price reaction to the State investment, 14 October 2026. Link
- Eramet, "Eramet launches a c.€500 million share capital increase with preferential subscription rights", 13 November 2026. Terms, State commitment, underwriting and timetable. Link
- Eramet, "Eramet lance une augmentation de capital avec maintien du droit préférentiel de souscription d'un montant d'environ 500 M EUR", 13 November 2026, with the prospectus summary (AMF approval 26-395, 12 November 2026): net proceeds, use of proceeds, the 100% gearing test at 30 June 2027 and the working-capital statement. Link
Note on figures. Company figures are Eramet's own. ZMK arithmetic: the €136m, €186m and €178m split of the raise, 19% of the wall, $14m per percentage point, the shares of the 150 kt headline, 38.5 Mwmt of 2025 external sales, 1.3% of transported ore, 285 days. ZMK calculations and assumptions: all Weda Bay thresholds and the achievable range. Not a valuation of Eramet or a recommendation on the shares or the rights issue.