RMB67.8 Billion of Claims: The Fall of He Jinbi, China’s Copper King
Maike Metals handled a quarter of China’s copper imports on a trading margin of about one per cent. Its founder has been sentenced to life, according to Bloomberg, and has appealed. Creditors have filed RMB67.8 billion (~US$10bn) of claims. The filings show who was paid, and who was handed trust units carried at zero.
Maike Metals handled a quarter of China’s copper imports on a trading margin of about one per cent.
- RMB67.8 billion (~US$10.1bn)claims filed against 26 Maike companies by 30 June 2025, in 863 separate claims1
- 1.29 per centMaike’s gross margin on metals trading in the first half of 2018, from its own bond prospectus
- RMB0the value an audited creditor puts on ordinary units in Maike’s 15-year bankruptcy trust, booked at an original cost of RMB160.4 million (~US$24m)
- RMB348.8 million (~US$52m)the gain a state-owned creditor booked on buying 75 per cent of Maike’s surviving logistics and property platform for RMB300 million (~US$45m)
863 claims
RMB67,761 million, or ~US$10.1bn. That is the value of the 863 claims creditors had filed against Xi’an Maike Metals International Group and 25 affiliated companies by 30 June 2025, according to a ruling of the Xi’an Intermediate People’s Court.2 The same ruling records that the court merged the 26 companies into one estate on 5 January 2024; a creditor’s filing gives the reason as highly commingled legal identities.3 On our calculation the claims equal 42 per cent of the RMB159.9 billion (~US$23.9bn) of revenue Maike booked in 2021, its best year.4
Last month a court in Xi’an found Maike guilty of contract fraud, bribery and other offences and sentenced its founder, He Jinbi, 61, to life in prison, according to people familiar with the verdict cited by Bloomberg on 26 October. The ruling found that Maike’s conduct exposed several Chinese banks to more than US$1 billion of potential losses, the people said. He has appealed. His defence argued that neither he nor the company intended to defraud anyone, that Maike had worked with its banks for more than a decade and regularly repaid its loans, including through the pandemic, and that some of the lenders’ losses came from their own weak internal controls. The judgment has not been published.5
He founded Maike with friends in 1993 on a 50,000 yuan loan (~US$8,700 at the time).5 By 2021 it was the 48th-largest private company in China by revenue, in the annual ranking of the All-China Federation of Industry and Commerce.6 It imported more than one million tonnes of refined copper a year, which it put at 29 per cent of China’s total imports in 2021.7 Bloomberg’s shorthand was one tonne in every four.5
The sentence will be read as a story about a tycoon. The filings tell a narrower and more useful story about a balance sheet. Maike earned a gross margin of a little over one per cent on the copper it sold, had about 40 per cent of its assets pledged or otherwise restricted, and borrowed against the paper its trades generated. Its lenders could read all of that in a bond prospectus four years before the collapse.
A one per cent business
Maike’s 2018 bond prospectus, filed with the Shanghai Stock Exchange, gave its gross margin on metals trading as 0.50 per cent in 2015, 1.76 per cent in 2016, 1.46 per cent in 2017 and 1.29 per cent in the first half of 2018. Revenue grew from RMB70.9 billion to RMB98.9 billion over the three full years.8 Jiemian reported revenue of RMB159.9 billion in 2021. In the first half of that year, according to Maike’s interim bond report as cited by Jiemian, refined copper was about 98 per cent of sales, at a gross margin of 1.4 per cent. Net profit ran between RMB249 million and RMB352 million a year from 2018 to 2020.4 On our calculation that is a net margin of between 0.2 and 0.3 per cent.
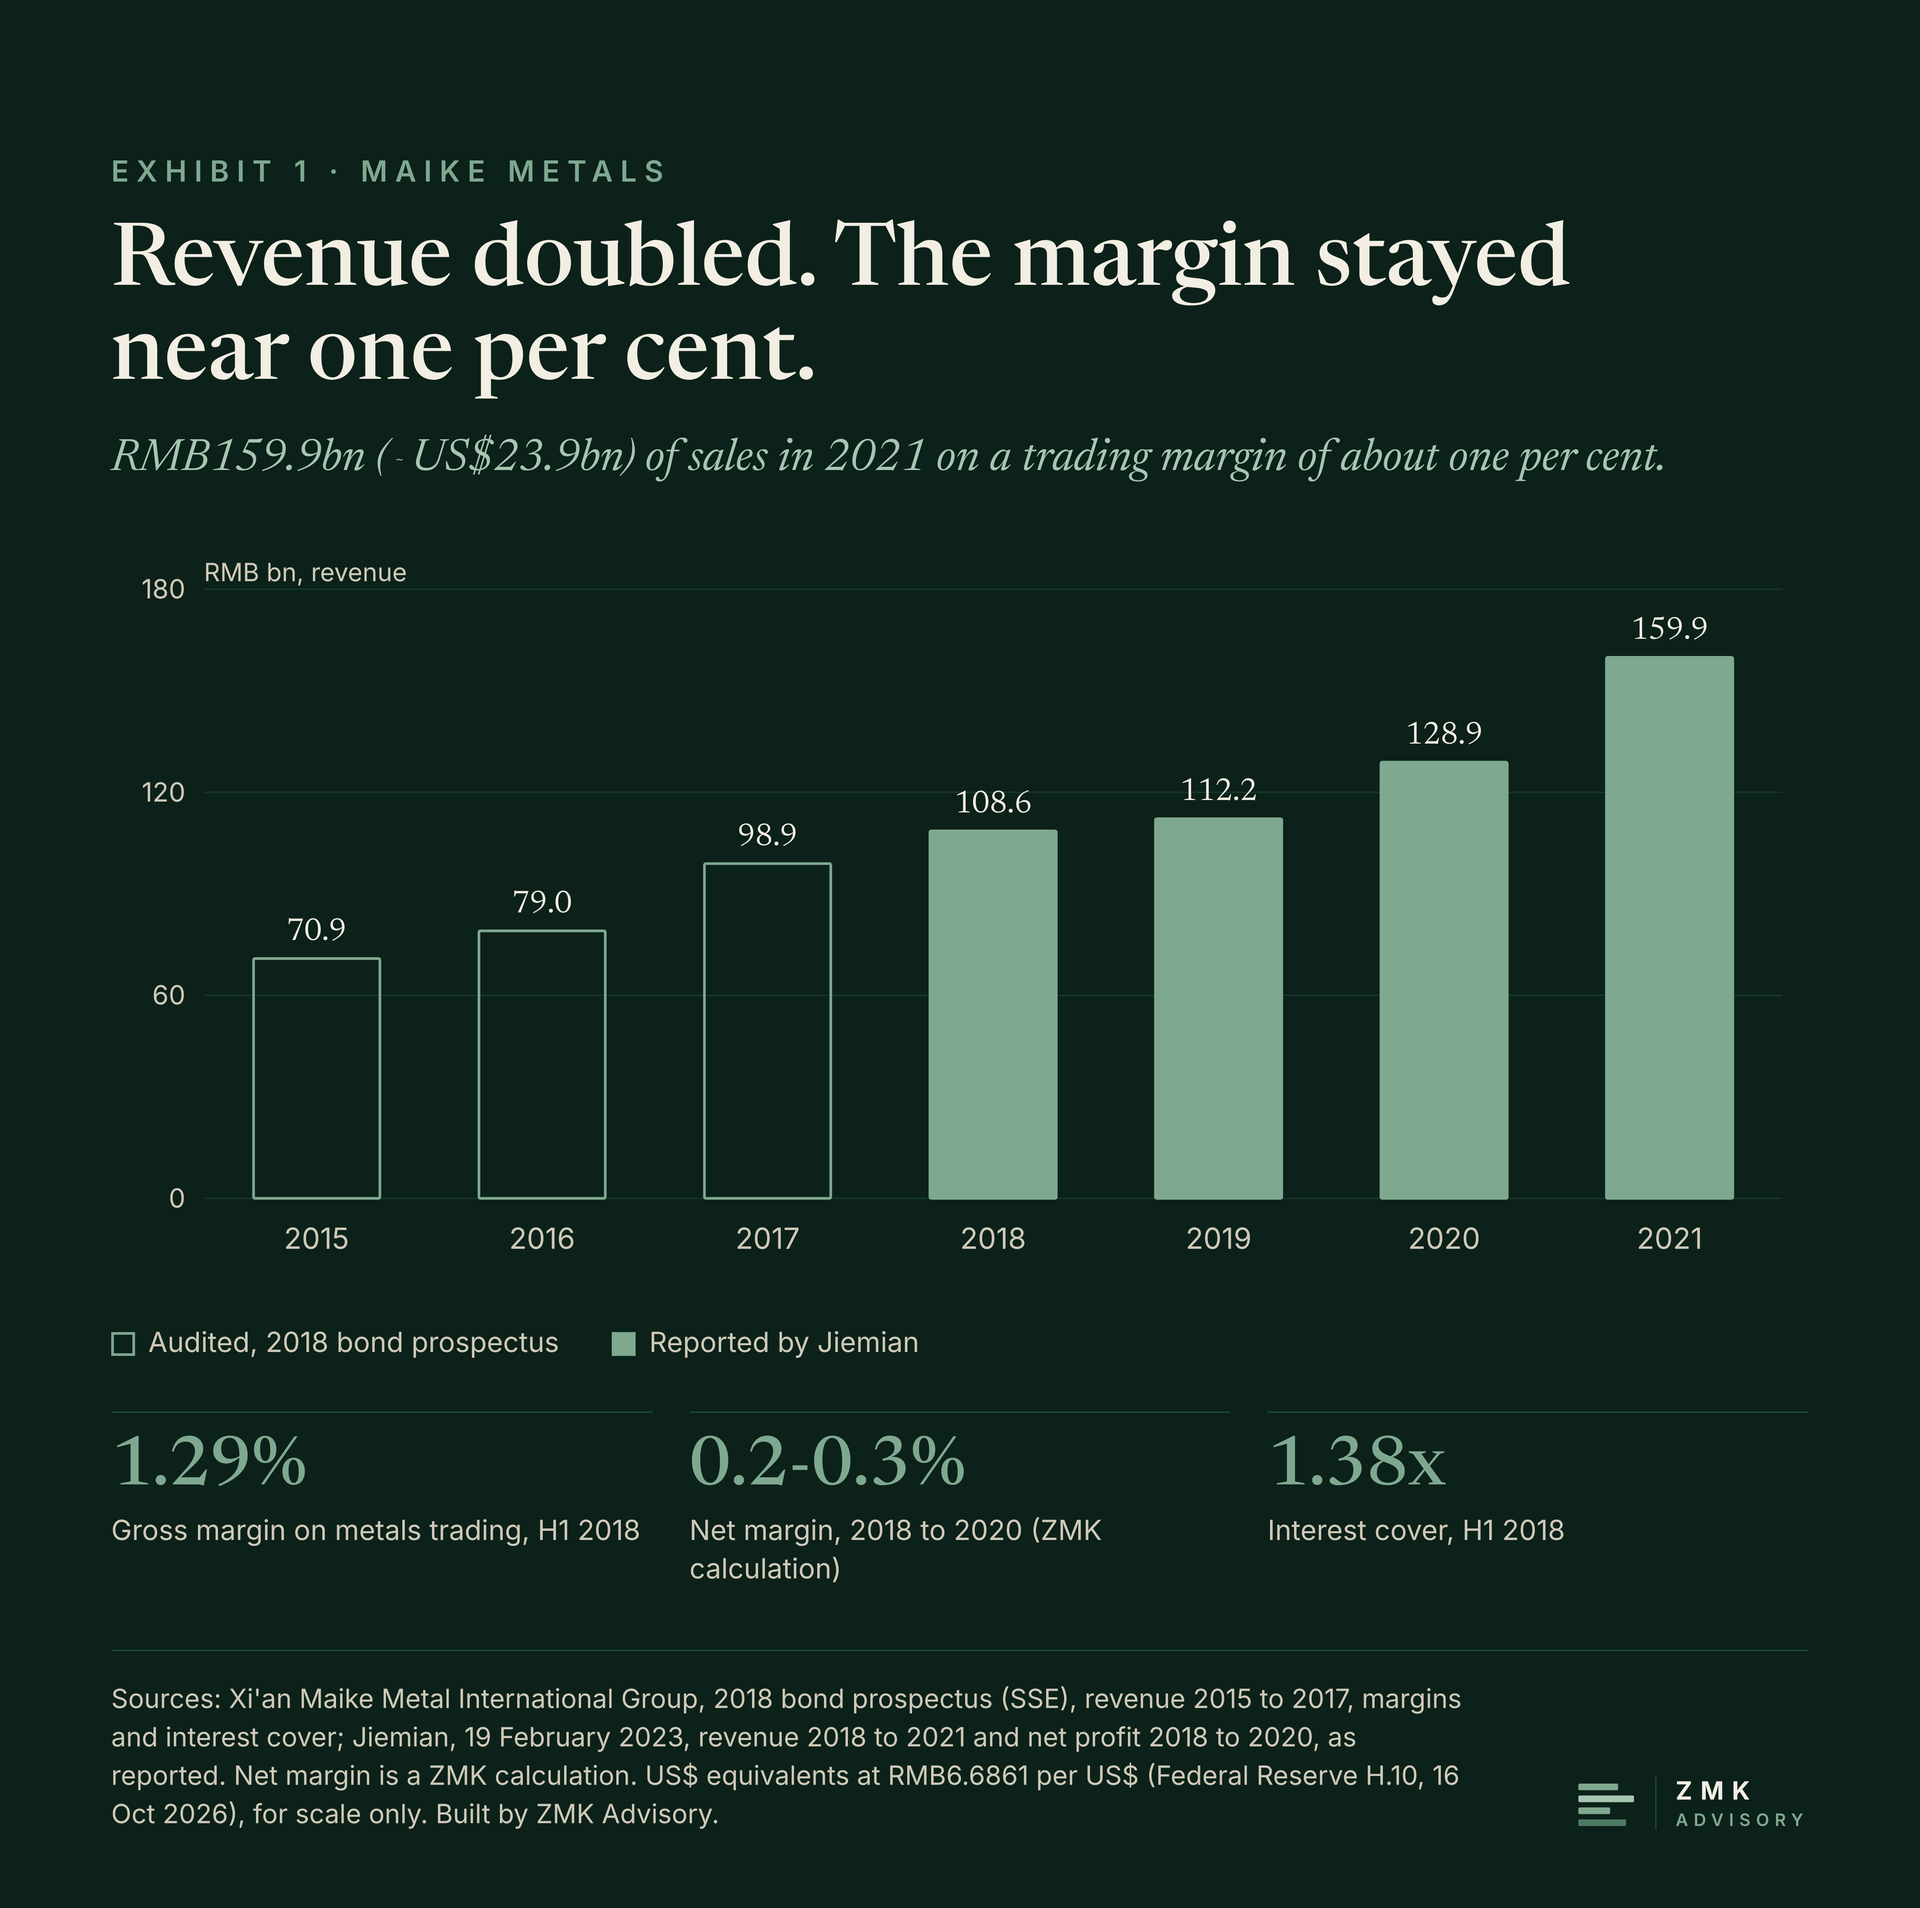
A trader on those margins is a funding business with a copper licence. Its profit is the spread between what it pays for money and what the market pays for metal while the cargo is afloat or in a warehouse. The prospectus shows the strain in its own ratios. Interest cover, defined as pre-tax profit plus interest divided by interest, fell in every period it reported: 1.62 times in 2015, 1.47 in 2016, 1.40 in 2017 and 1.38 in the first half of 2018. The current ratio stood at 0.76. Restricted assets, meaning assets pledged to lenders or otherwise tied up, including cash held as margin, were RMB9.42 billion (~US$1.4bn) at 30 June 2018, or 40.8 per cent of the total. The rating agency, Lianhe, flagged large restricted assets, a heavy debt burden, short-term repayment pressure and low interest cover in the same document.8
Three years later the position had moved the wrong way. At 30 June 2021 Maike reported total assets of RMB24.15 billion (~US$3.6bn), liabilities of RMB17.7 billion (~US$2.6bn) and restricted assets of RMB11.36 billion (~US$1.7bn).4 On our calculation 47 per cent of the group’s assets were restricted, at the top of the copper cycle.
Then the cycle turned. Lockdowns in Shanghai and Xi’an from March 2022 hit both Maike’s copper imports and its property business, Caixin reported.9 The IMF’s monthly copper price averaged US$10,231 a tonne in March 2022 and US$7,545 in July, a fall of 26 per cent in four months on our calculation.10 Bloomberg lists that fall alongside Covid restrictions and a property downturn that hit Maike’s hotels and offices.5 He later told the Economic Observer that some bank loans repaid in 2022 were hard to roll over.11 For a borrower earning about one per cent on its turnover, a quarter off the price of its collateral is a problem it cannot solve from earnings.
The machine
Bloomberg describes He as a pioneer of borrowing against the metal he shipped and stored.5 The prospectus describes a second engine that drew less attention. Maike’s commodity financial-services subsidiary in Shenzhen collected bills from customers, the post-dated payment orders that Chinese companies use in place of cash. Maike did not discount them. It pledged them to domestic financial institutions, which issued guarantees that let it raise money offshore to pay for copper cargoes. When the bills matured, the domestic institution paid Maike the face value. Maike booked the difference between what its customers owed and the face of the bills as interest income: RMB79 million in 2015, RMB79 million in 2016, RMB75 million in 2017 and RMB90 million in the first half of 2018. The prospectus called it a major future source of profit.8
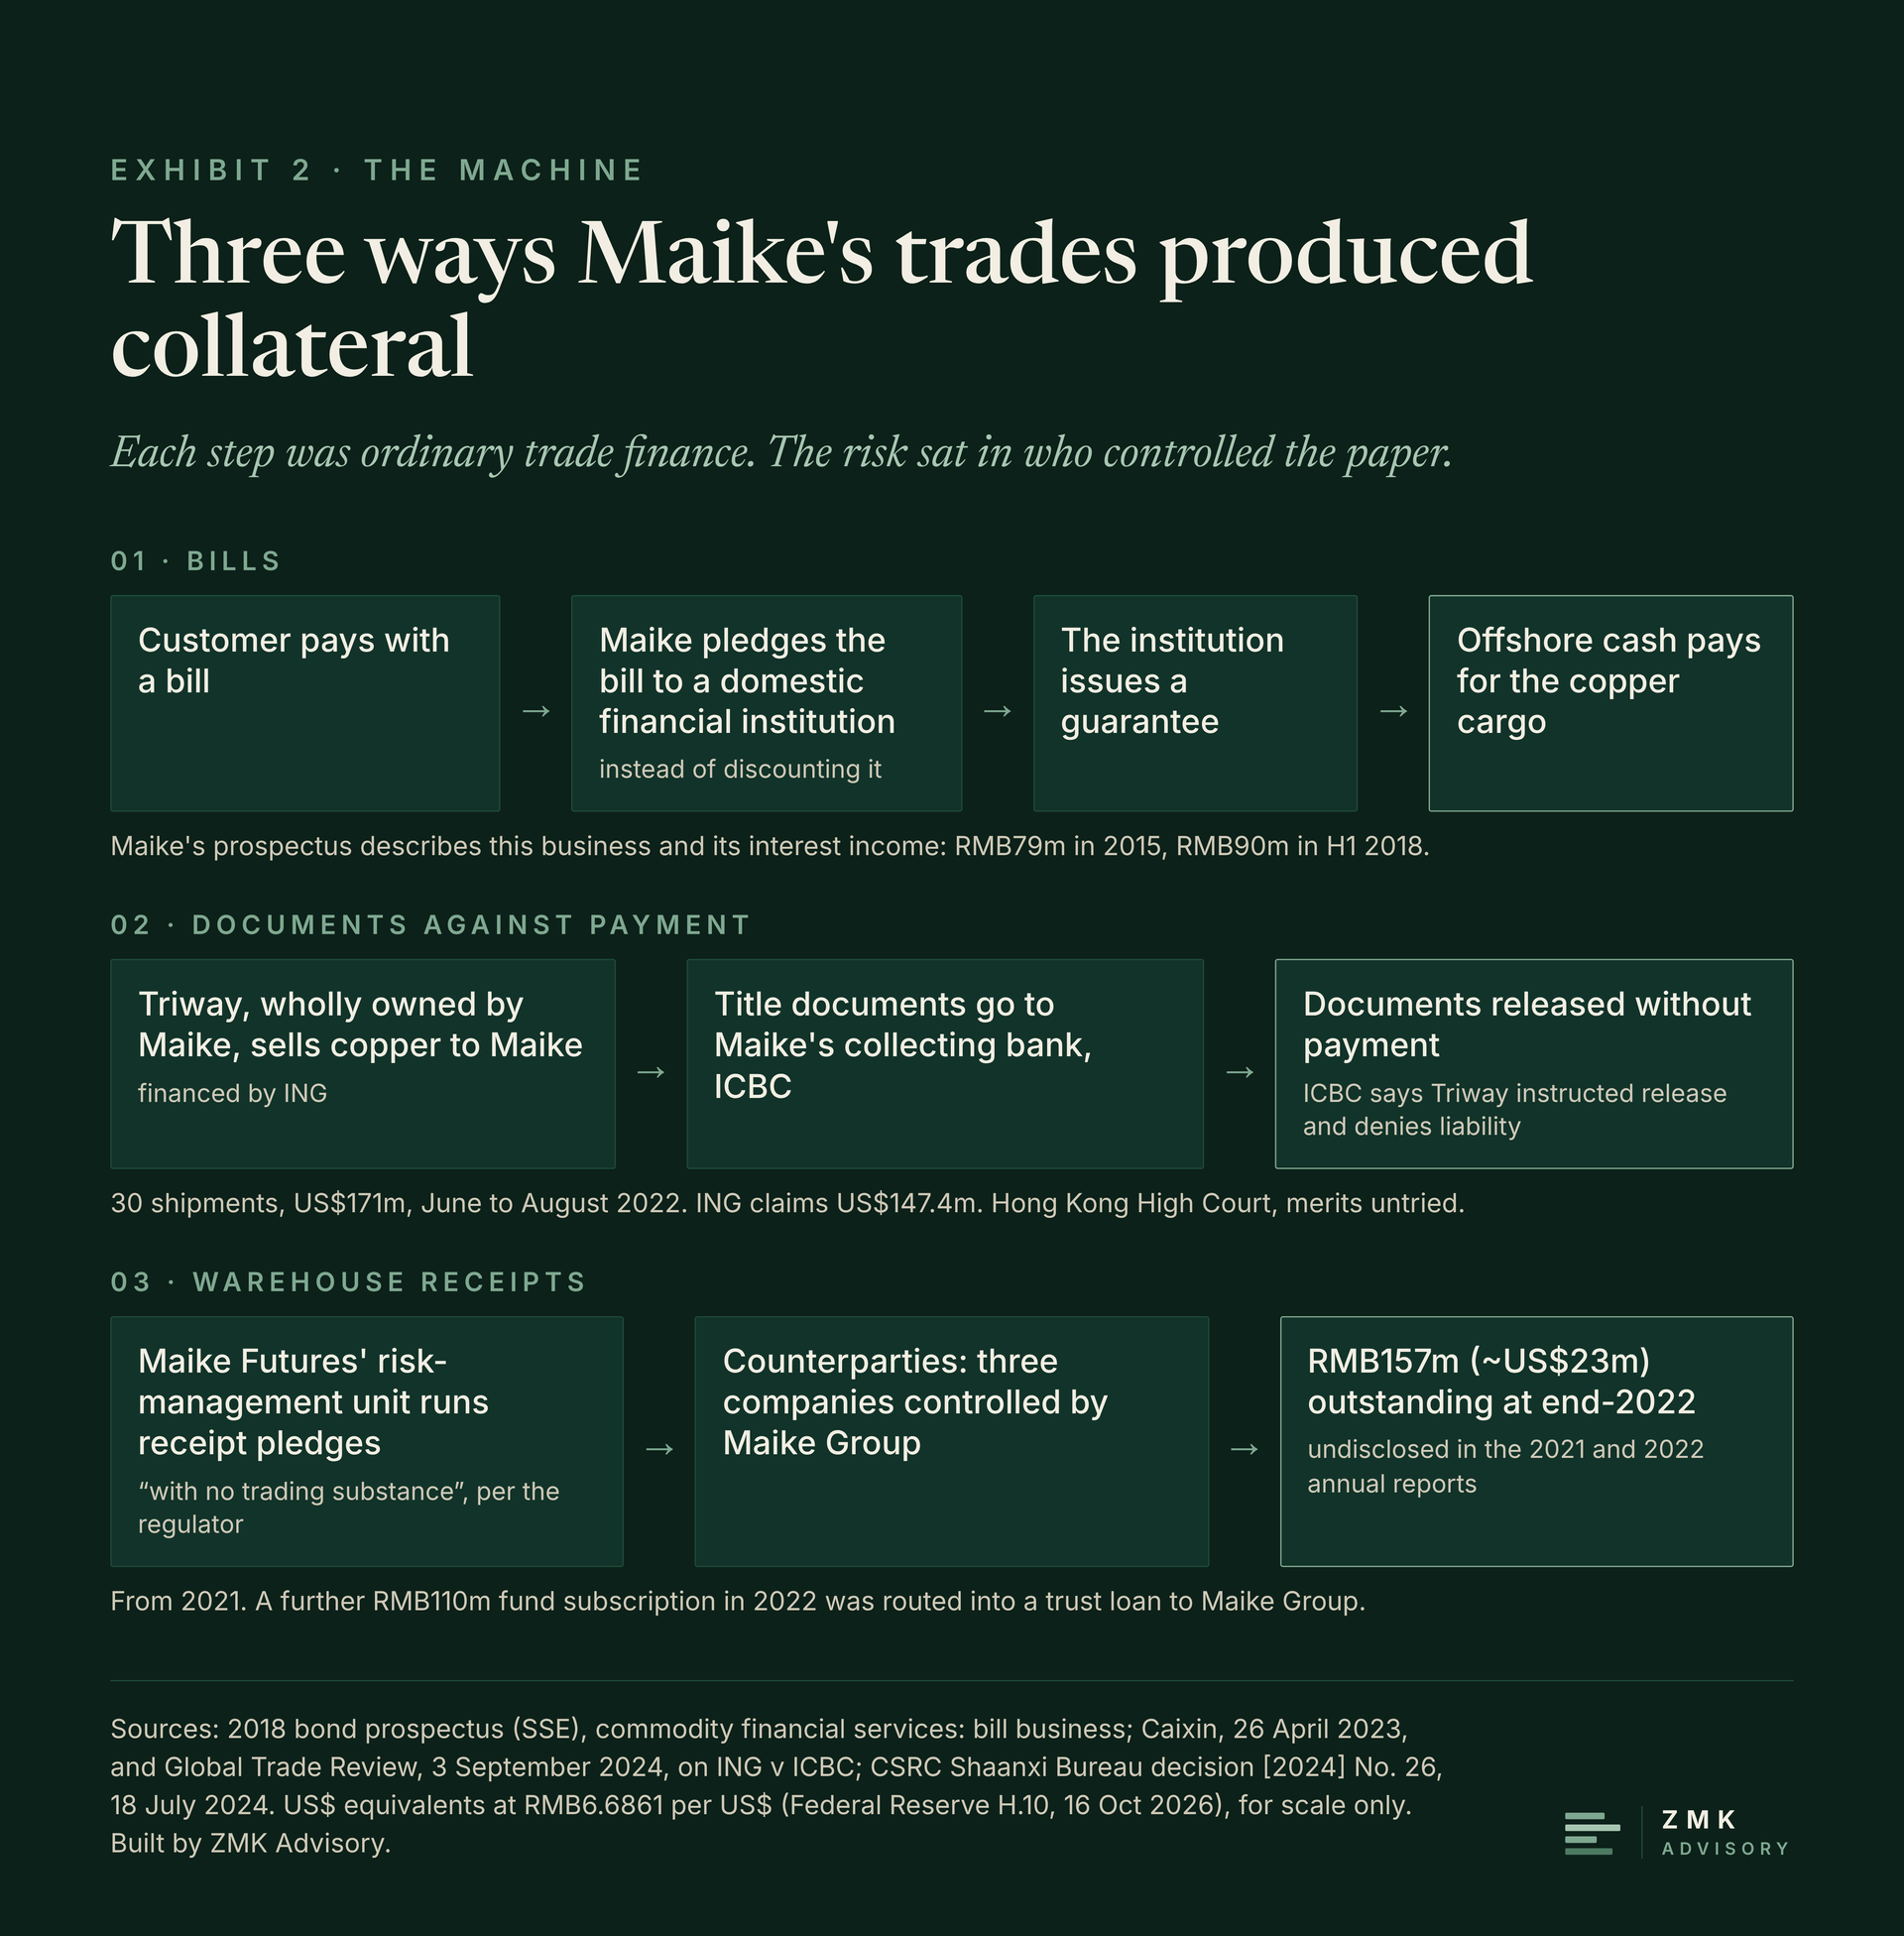
Nothing in that description is unlawful. It is the ordinary architecture of Chinese commodity finance, and it explains the scale. The prospectus says Maike generally paid for imported cargoes on documents-against-payment or telegraphic-transfer terms.8 On our reading, a trader that pays against documents can carry a cargo on bank credit from the moment those documents are presented. In principle one cargo can support a letter of credit, a pledged bill and a warehouse receipt in turn. Whether two financiers are lending against the same tonne is the question each lender has to answer for itself. We found no published source alleging that Maike pledged the same metal twice.
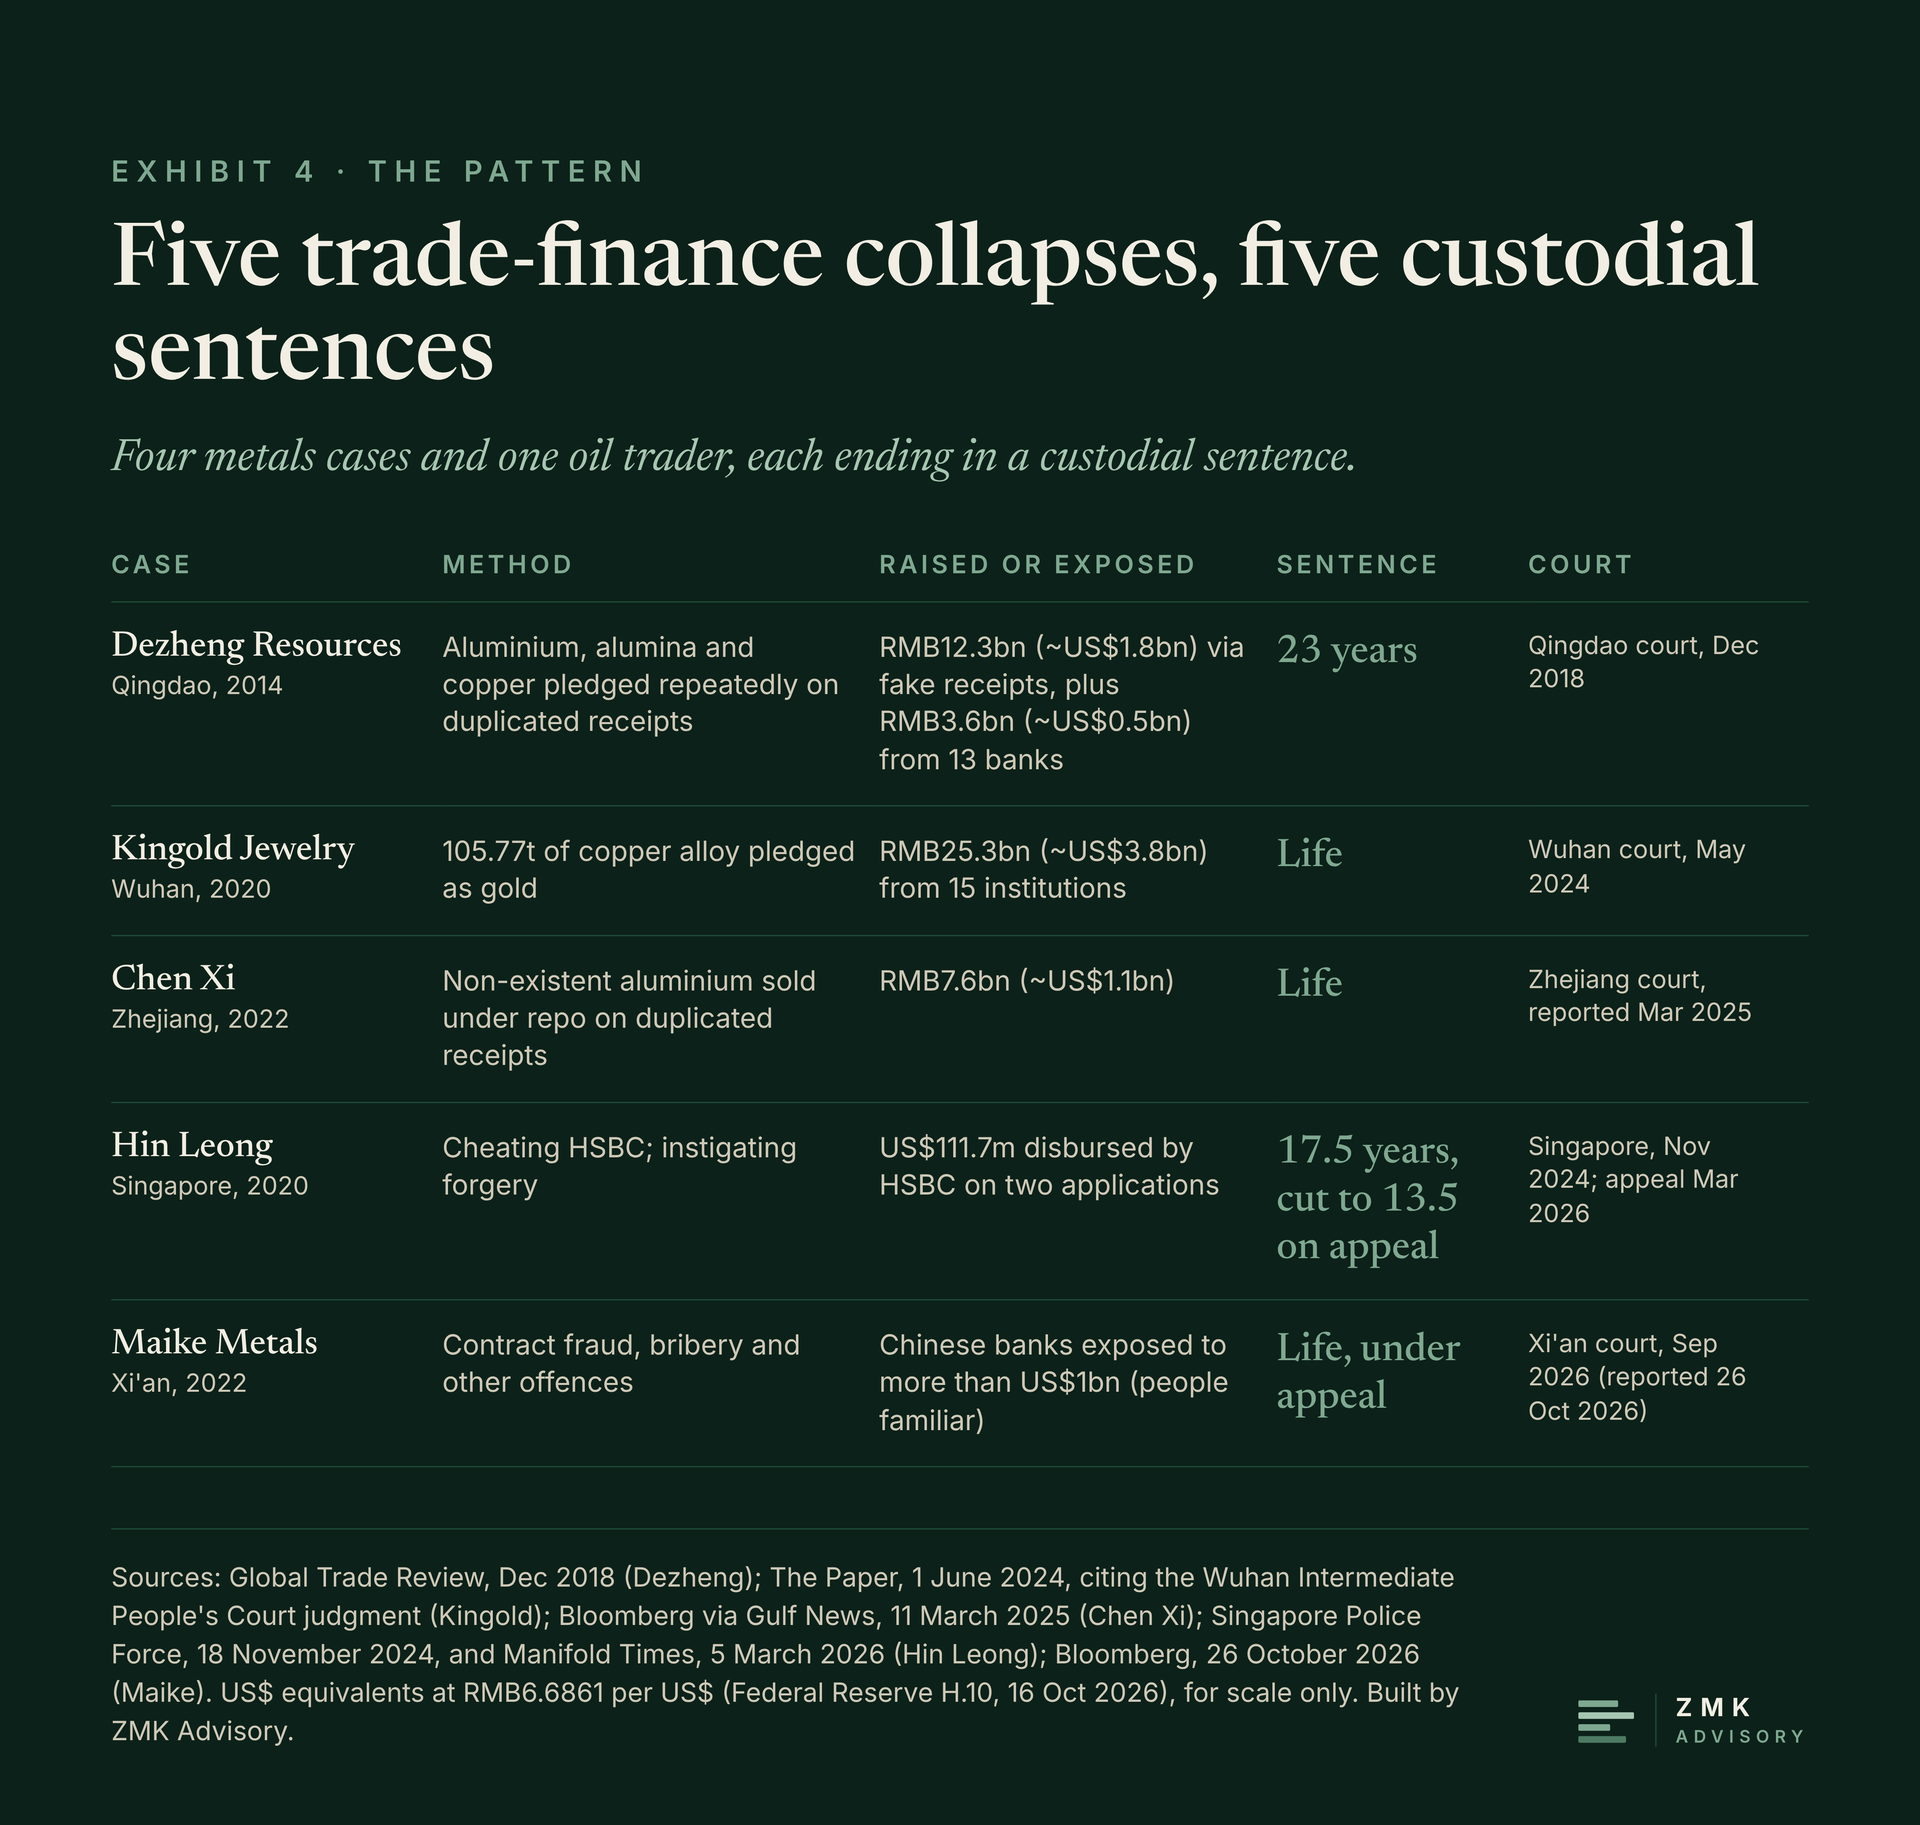
China’s regulators knew the risk. In May 2013 the State Administration of Foreign Exchange ordered banks to apply know-your-customer checks to spot fictitious trade and promised severe penalties for arbitrage using false documents.12 A year later the Qingdao port scandal broke. Dezheng Resources had pledged the same aluminium, alumina and copper several times over with forged and duplicated warehouse receipts. It raised RMB12.3 billion (~US$1.8bn) through fake receipts and a further RMB3.6 billion (~US$540m) in loans, letters of credit and bank acceptance bills from 13 banks. In December 2018 its chairman, Chen Jihong, was sentenced to 23 years.13 Maike came through both episodes and kept growing.
Civil litigation in Hong Kong points to the documents side. Between June and August 2022 Triway International sold 30 shipments of copper worth US$171 million to Maike on documents-against-payment terms, under which title documents are handed over only when the buyer pays.14 Triway is a Hong Kong company wholly owned by Maike, with He Jinbi as a director, according to Caixin’s search of the company register.15 ING financed Triway, and ICBC acted as the collecting bank for Maike. ING says ICBC released the documents without collecting payment and claims US$147.4 million. ICBC says Triway instructed it to release them and that the practice was common. In August 2024 the Hong Kong High Court refused ICBC’s bid to move the case to the mainland, and the judge observed at that preliminary stage that the release was “quite contrary to the express terms of the collection instructions”. The merits have not been tried.14 Separately, ING is suing He personally in Hong Kong for US$147 million under his guarantee of Triway’s debts.16
On our reading the structure is the point. Seller and buyer were the same group. ING’s security was a receivable owed by Maike to its own subsidiary, and it depended on documents passing through Maike’s own bank.
The third channel ran through Maike Futures, the brokerage quoted on Beijing’s NEEQ market in which Maike holds 83.17 per cent. On 18 July 2024 the Shaanxi bureau of the China Securities Regulatory Commission found that from 2021 the brokerage’s risk-management subsidiary had run warehouse-receipt pledge business “with no trading substance” with three companies controlled by Maike Group, arranged by a director to occupy the brokerage’s funds. In 2022 the brokerage also put RMB110 million into a private fund that was routed into a trust loan to Maike Group. The diverted money stood at RMB30 million at the end of 2021 and RMB267 million (~US$40m) at the end of 2022, or 41 per cent of the brokerage’s audited net assets. None of it was disclosed in the 2021 or 2022 annual reports. The regulator issued warning letters to Maike Group and to He Jinbi, and found him primarily responsible as actual controller.17 The pledges began in 2021. Caixin, citing its own reporting, dates Maike’s debt crisis to October 2021, almost a year before the company acknowledged it.15
Who got paid
The market moved before the courts did. On a Sunday at the end of August 2022 the Xi’an municipal government hosted a meeting between Maike and its domestic banks. The lenders agreed to credit support, including extensions on existing loans.18 In the same weeks BHP and Codelco paused sales to Maike and diverted cargoes, and ICBC Standard Bank moved copper backing its Maike loans out of China.19 JPMorgan and ICBC Standard cut financing to other Chinese metals traders.20 The government brokered forbearance. The international counterparties stopped shipping, and one lender moved its collateral offshore.
Among the first domestic creditors to act was a state trader. In January 2023 Xiamen Xinda, a state-owned company listed in Shenzhen, brought four arbitrations against Maike companies and He personally for about RMB1.085 billion (~US$162m). Its filing records that Maike and He had guaranteed Xinda’s business with them up to RMB2.8 billion (~US$419m) for the year to March 2022 and RMB2.0 billion (~US$299m) for the year to March 2023.21 Both figures are caps, not amounts owed. On a partial award, Xinda took a 12.86 per cent stake in Qingtongxia Aluminium from Maike in 2023. An independent valuer had put that stake at RMB967.2 million (~US$145m) at 31 August 2022.22 He told the Economic Observer in February 2023 that the Xi’an government had set up a task force and that the restructuring would be “government-led”, on a market-based and law-based path.11
Maike applied to the Xi’an court for pre-restructuring on 17 February 2023.7 It did not file the bankruptcy that followed. The court accepted a petition from a creditor, Hainan Gaoke Trading, on 13 November 2023.23 Hainan Gaoke is a subsidiary of Xi’an Gaoke Group, a local state-owned enterprise, according to Shangyou News’s review of company records.23 Executives had lost contact with He in early October 2023 and believed he had been taken by police in Shaanxi for questioning.24
The court’s claims register shows who carried the risk. The second batch of uncontested claims, confirmed in a ruling dated 27 June 2025, covers 106 creditors and RMB4.52 billion (~US$676m). Its largest secured entries are Chang’an Bank’s Xi’an Hi-Tech branch at RMB1.19 billion (~US$178m), the Shaanxi branch of China CITIC Financial Asset Management at RMB976 million (~US$146m), Xiamen Asset Management at RMB572 million (~US$86m) and the Agricultural Bank of China’s Xi’an Yongningmen branch at RMB318 million (~US$48m). The largest unsecured entries are two creditors at RMB481 million (~US$72m) and RMB284 million (~US$43m).2 The batch is 6.7 per cent of the RMB67.8 billion filed. Filed claims are not admitted claims, and the register published so far does not reconcile to the headline.
The plan the court approved on 30 September 2025 split the estate in two.3 Logistics facilities in Shanghai’s free-trade zone and offices in Shanghai, Xi’an and Shenzhen went into a new platform company. An independent valuer put those assets at RMB1,456.7 million (~US$218m) against a book value of RMB817.9 million (~US$122m). Investors competed for 75 per cent of the platform at a fixed price of RMB300 million (~US$45m) in cash, half paid to the administrator and half into the platform as capital. The mortgages on the properties stay with them and must be repaid by 30 September 2032. Everything else went into a bankruptcy service trust run by Shaanxi International Trust, which also holds the other 25 per cent of the platform.3
Xinda was selected. Its 2025 accounts, which also record an earlier arbitration award of RMB125.8 million (~US$19m) against Maike in December 2022, treat 31 December 2025 as the date it took control. It valued its 75 per cent share of the platform’s net assets at RMB648.8 million (~US$97m) and booked the RMB348.8 million (~US$52m) difference over the price as a bargain-purchase gain in non-operating income; under the plan its claims were converted into trust units.25 Its own confirmed unsecured claim was RMB359.8 million (~US$54m).3
The other creditors received trust units. Claims were converted at face value into ordinary units for unsecured debt and priority units for secured debt whose collateral sits outside the platform. The trust runs for 15 years, operating the assets for ten and selling them in years 11 to 15. Maike Futures is the one creditor we found that discloses an audited value for its units. It carries its ordinary units, booked at an original cost of RMB160.4 million (~US$24m), at zero, because the debtor was insolvent and nothing can be sold before year 11. It carries priority units with an original value of RMB110 million (~US$16m) at RMB58.2 million (~US$8.7m).26
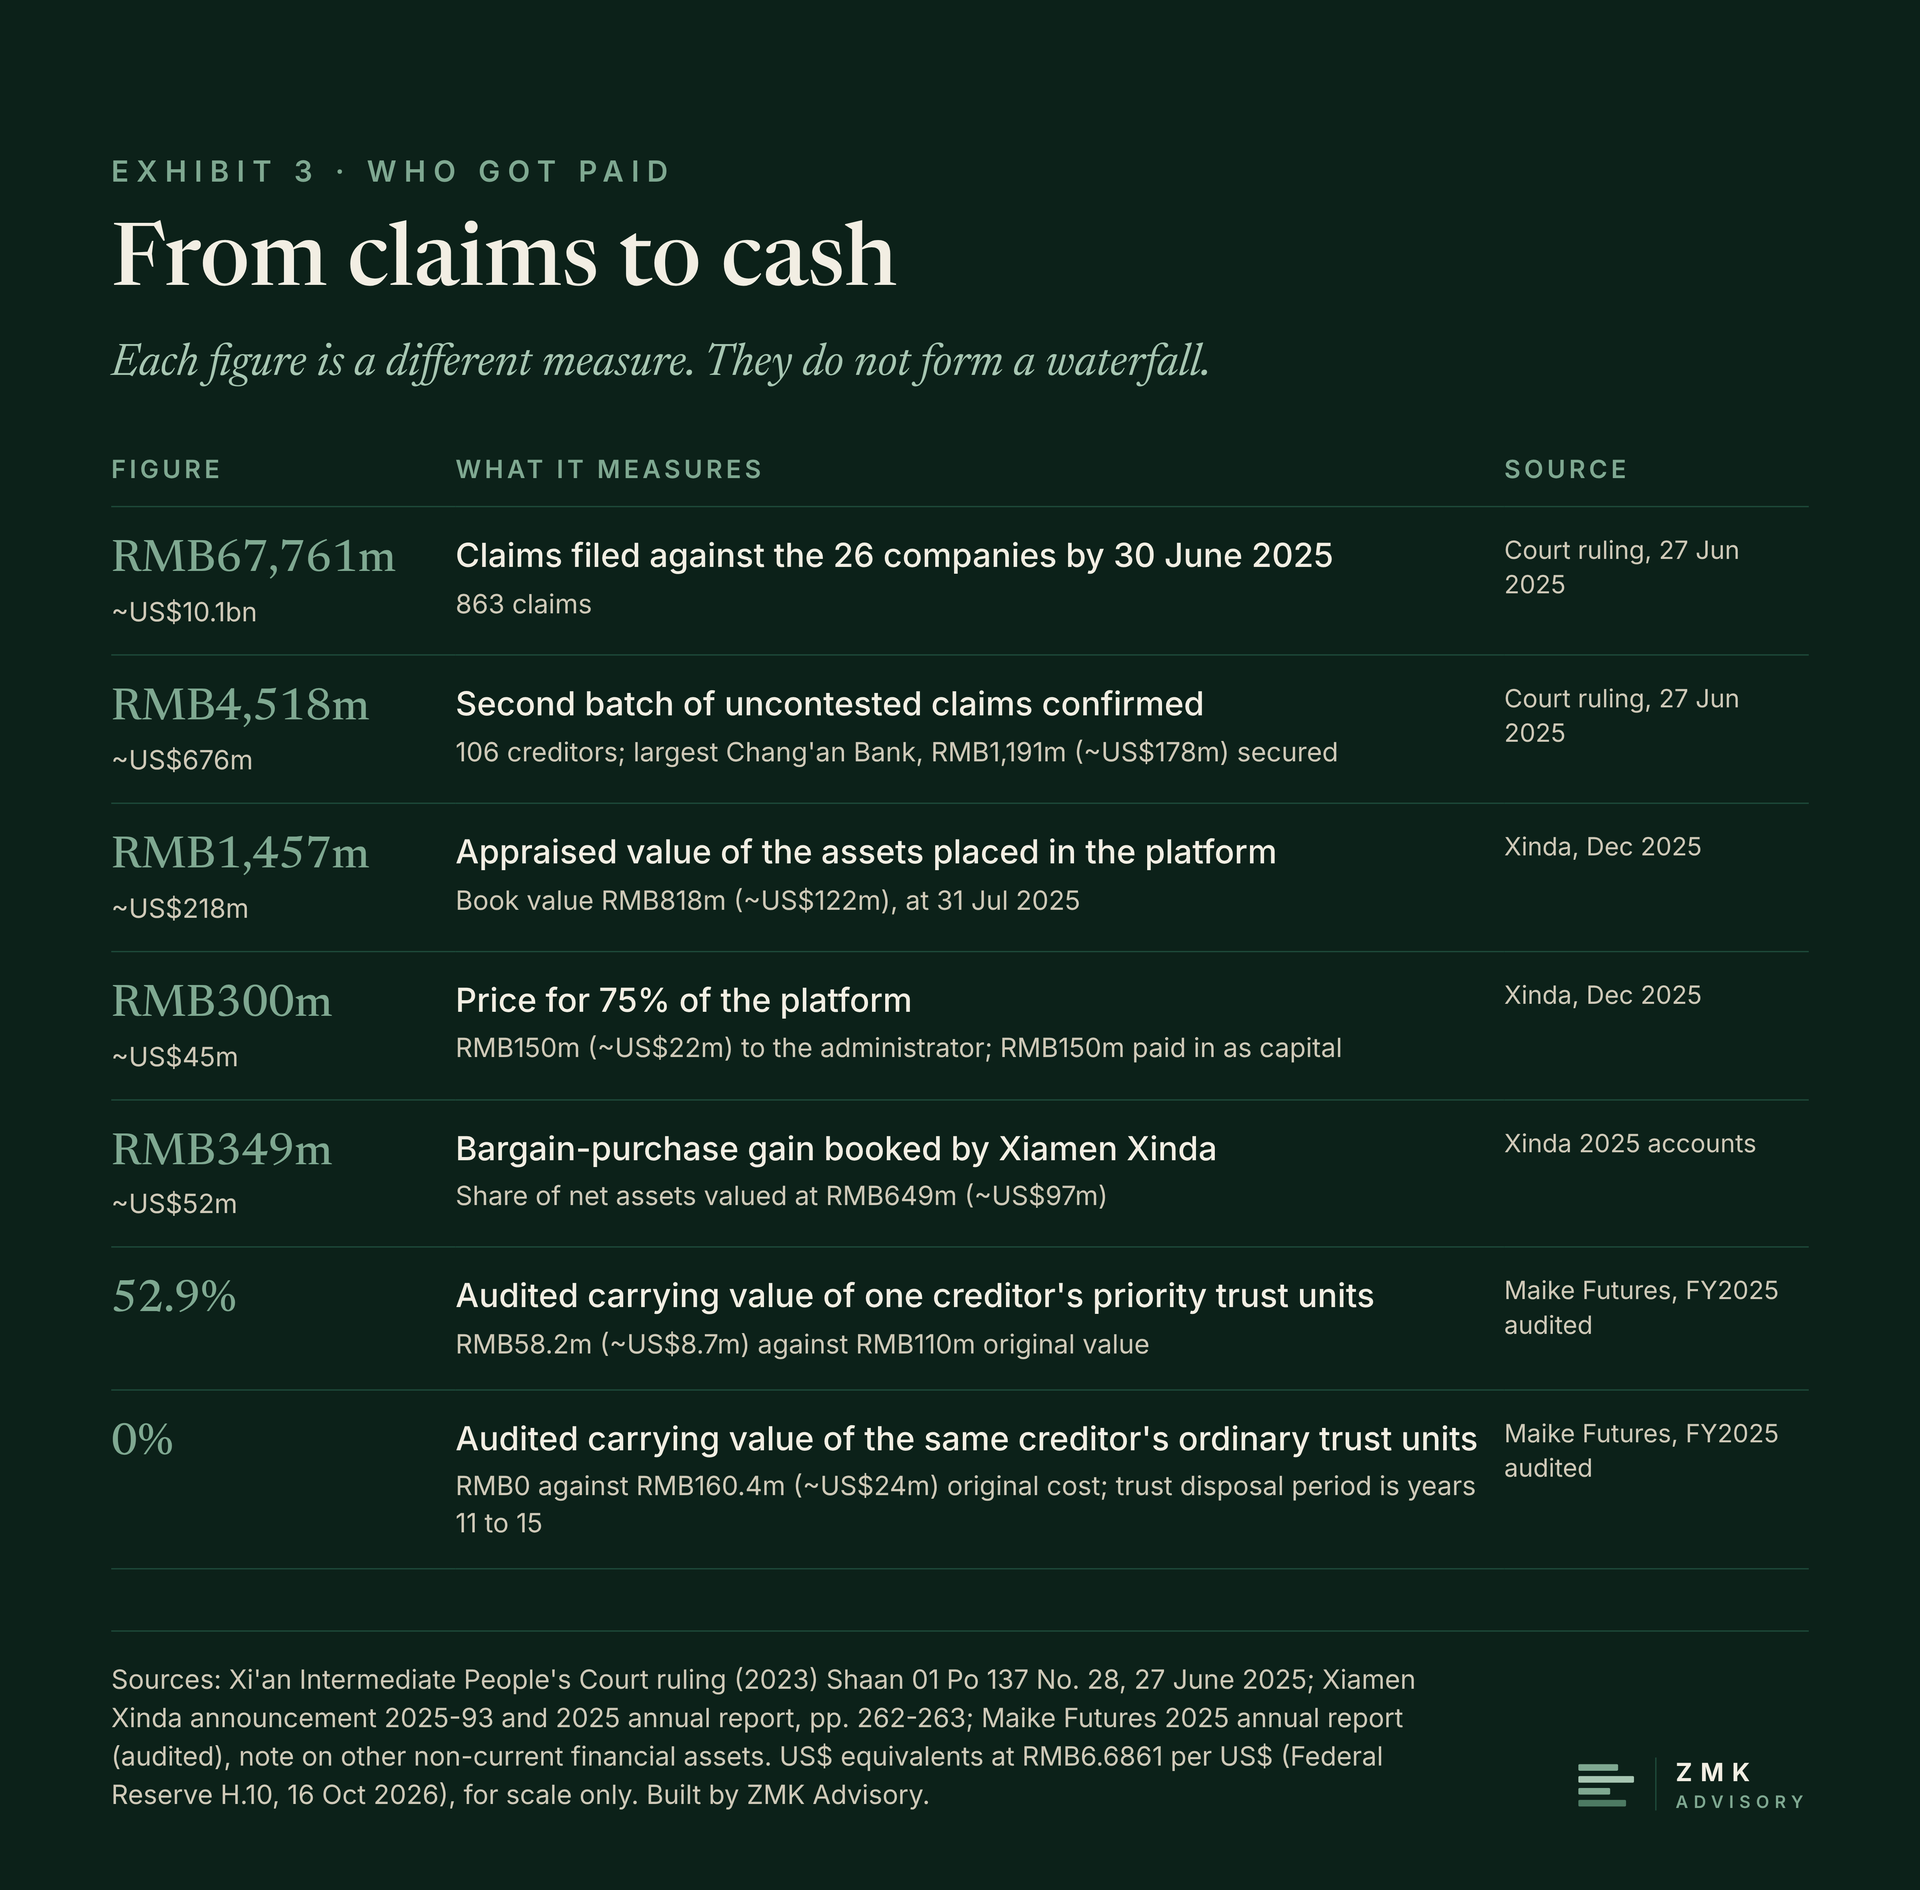
On our calculation the RMB150 million (~US$22m) paid to the administrator is 0.22 per cent of the claims filed. That ratio measures cash paid into the estate, which is a different thing from what creditors will recover, and no recovery rate has been published. One audited creditor’s marks put its unsecured recovery at zero and its secured recovery at 53 per cent of principal. Xinda, among the first creditors to move, holds an aluminium stake, control of the platform the plan carved out of the estate, and an accounting gain.
What changes on Monday
Life sentences are no longer unusual in large trade- and financial-fraud cases in China. In May 2024 a Wuhan court sentenced Jia Zhihong of Kingold Jewelry to life for contract fraud and bribery offences. His group had raised RMB25.3 billion (~US$3.8bn) from 15 institutions against 105.77 tonnes of “gold” that turned out to be copper alloy.27 Bloomberg reported in March 2025 that a Zhejiang court had given the aluminium trader Chen Xi a life term for selling non-existent metal under repurchase agreements backed by duplicated inventory receipts, raising RMB7.6 billion (~US$1.1bn).28 In August 2026 the Evergrande founder Hui Ka Yan received the same sentence for financial fraud.29 Outside China, Singapore jailed Hin Leong’s founder Lim Oon Kuin for 17.5 years for cheating HSBC and instigating forgery.30 On appeal the High Court cut the term to 13.5 years in March 2026.31
Lenders do not see this tail in their headline statistics. The ICC Trade Register reported obligor default rates of 0.37 per cent on import letters of credit and 0.76 per cent on import and export loans for 2008 to 2018.32 Those figures are reported by product. Losses on a duplicated receipt or a document released without payment are not shown separately.
The Maike record supports five checks, each testable against any trading counterparty.
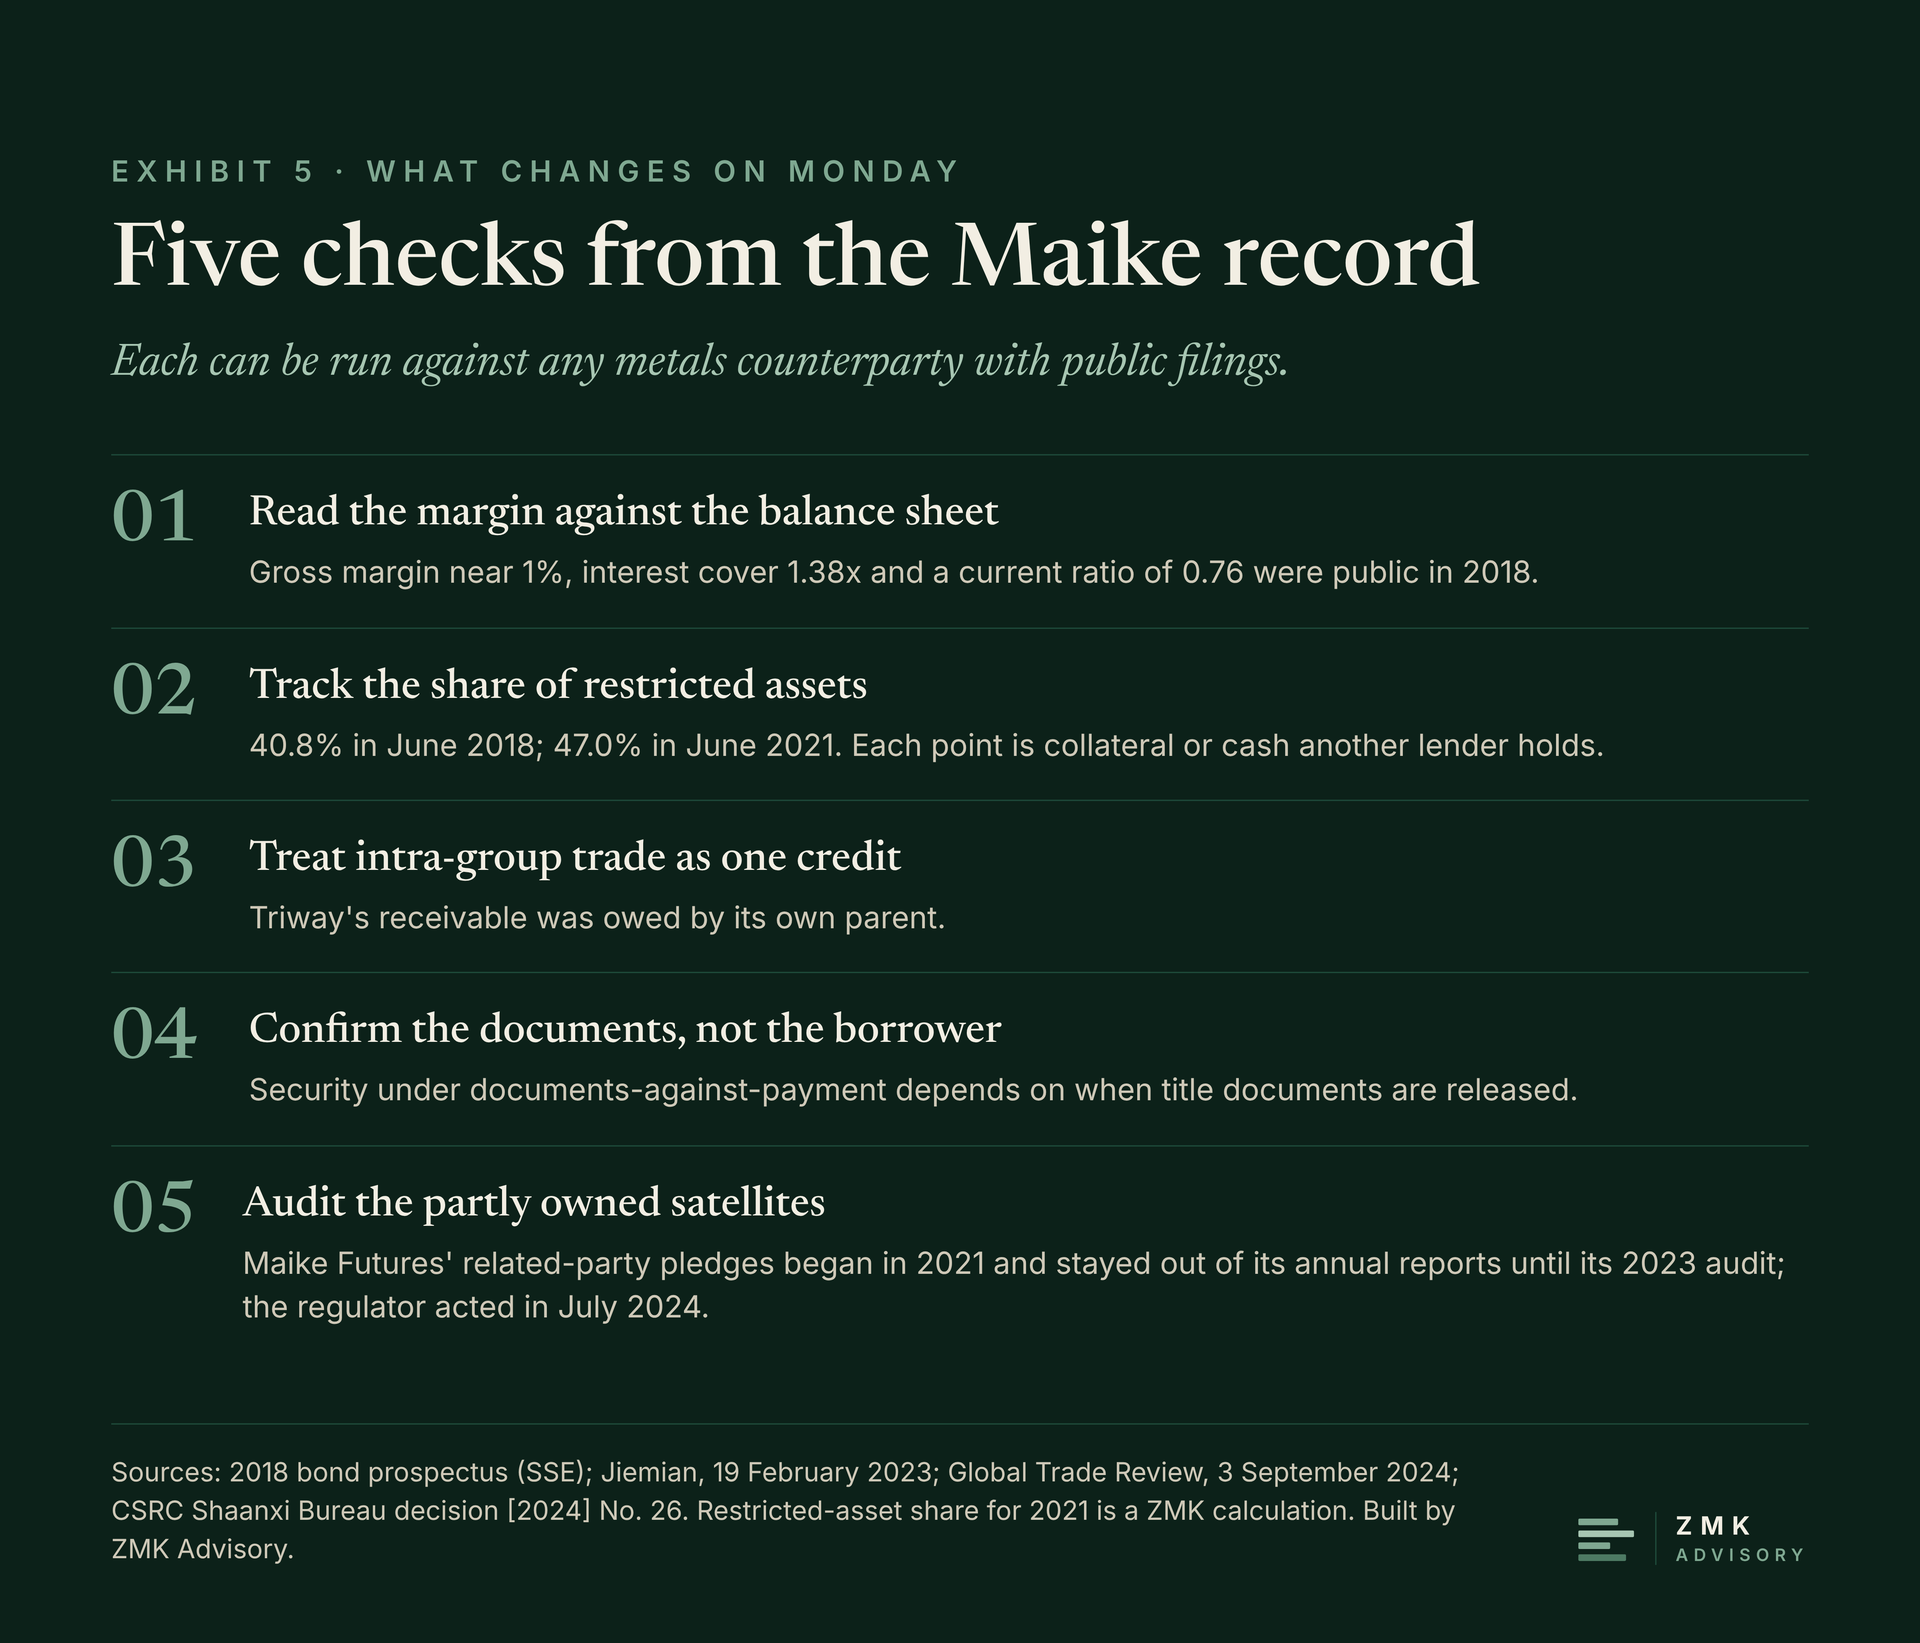
Read the margin against the balance sheet. A gross margin near one per cent, interest cover below 1.5 times and a current ratio below one were all in a public prospectus in 2018. They describe a borrower that cannot absorb a price shock from earnings.
Track the share of restricted assets. Maike’s rose from 41 per cent in 2018 to 47 per cent in 2021. Each point is collateral or cash another lender already holds.
Treat intra-group trade as one credit. A receivable owed by a parent to its own offshore subsidiary is the group’s credit, whatever name is on the invoice.
Confirm the documents, not the borrower. Under documents-against-payment, the security is only as good as the collecting bank’s control of the title documents. A lender that cannot see when they are released does not hold the security it priced.
Audit the partly owned satellites. Maike Futures’ related-party pledges ran from 2021 and stayed out of its annual reports until its 2023 audit, after which the company disclosed them and the regulator acted. The quoted subsidiary is where a controlling shareholder’s cash stress can show first, and where it can be hidden.
About 14 months separated the government-hosted bank meeting at the end of August 2022 from the court’s acceptance of a creditor petition in November 2023. The arithmetic did not change in between. RMB67.8 billion of claims, ~US$10.1bn, now sits against a business that earned about one per cent on its copper. A state-owned creditor booked a gain, and an audited creditor carries its unsecured units at zero. For any lender, trader or investor with counterparty exposure in metals, the useful question is how much of their own book is lent against the paper that trades generate rather than the metal itself. That is the question ZMK Advisory puts to the clients it advises on counterparty, trade-finance and commodity risk.
Every Field Note goes live on this site first, then on LinkedIn and X.
Follow ZMK Advisory to see the next one on the day it publishes.
This Field Note on LinkedInRead the discussion, or add to it →Status of proceedings. The criminal judgment against Maike and He Jinbi has not been published. Its existence, the offences, the sentence and the US$1 billion exposure figure are reported by Bloomberg on 26 October 2026 from people familiar with the verdict. We searched Chinese court, procuratorate and discipline-commission sources and found no official notice; every Chinese-language report we found relays Bloomberg. “Last month” in Bloomberg’s report places the verdict in September 2026; the exact date is not public. He Jinbi has appealed, and the conviction is not final. Who received bribes has not been disclosed, and nothing here suggests who they were. The CSRC Shaanxi decision of 18 July 2024 is an administrative supervisory measure, not a criminal finding, and is not presented as part of the criminal case. ING’s claims against ICBC and against He are civil proceedings in Hong Kong; the 2024 ruling concerned jurisdiction only. Nothing in this article asserts that any bank, trader, creditor or individual other than those convicted acted unlawfully. Xiamen Xinda’s recoveries and gain were obtained through arbitration and a court-supervised, competitive process.
Our calculations. Claims to 2021 revenue: 67,761 / 159,878 = 42.4%. Restricted assets at 30 June 2021: 11,359 / 24,152 = 47.0%. Net margin 2018 to 2020: between 0.21% and 0.31% depending on how reported profit is matched to year (see below). IMF copper, March to July 2022: 7,544.81 / 10,230.89 − 1 = −26.3%. Second-batch confirmed claims to total filed: 4,518.10 / 67,761 = 6.7%. Cash to administrator to claims filed: 150 / 67,761 = 0.22%. Platform appraisal to book: 1,456.66 / 817.87 = 1.78. Revenue 2015 to 2021: 159,878 / 70,880 = 2.26 times. Xinda gain: 648.83 − 300.00 = 348.83, as stated in its accounts. Maike Futures priority units: 58.21 / 110.00 = 52.9% of original value; 58.21 / 121.64 (confirmed claim including interest) = 47.9%. Bank meeting (28 August 2022, the Sunday before Bloomberg’s 1 September report) to acceptance of the creditor petition (13 November 2023): 442 days, described in the body as about 14 months. All calculations are in the currency reported. US dollar equivalents in the body are for scale only, at a single reference rate of RMB6.6861 per US dollar (Federal Reserve H.10, 16 October 2026); they are not the dollar values at the date of each figure. At the 30 June 2025 rate of RMB7.1636, the date of the claims total, RMB67.761bn would be ~US$9.5bn. The 50,000 yuan founding loan is converted as Bloomberg reported it, at the rate of the time.
Comparability. The 2015 to H1 2018 figures come from Maike’s audited accounts as presented in its 2018 bond prospectus. The 2018 to 2021 figures are as reported by Jiemian; the 2020 and 2021 revenue figures match the federation’s published lists, and the June 2021 balance sheet matches the Economic Observer’s figures. Jiemian gives net profit of RMB271m for 2019 and RMB352m for 2020; another outlet reverses the two, so the body gives the range only. The prospectus gives two figures for the 2015 consolidated gross margin (0.69% and 0.74%); the body uses the metals-trading margin, which is stated once. Restricted assets include pledged assets, pledged equity and restricted cash such as margin deposits. The 29% import share is Maike’s statement to Reuters. Bloomberg’s “quarter”, the prospectus’s “30 to 40 per cent” of the cathode trade and Caixin’s 40% of 2020 imports measure different things and are not used as data. The IMF series is a monthly average, not the LME daily settlement. The RMB67.8bn claims figure is claims filed, which can include interest, penalties, guarantee claims and contested or overlapping amounts; it is not the group’s liabilities and is not compared with the June 2021 liabilities in the body. The US$1bn exposure in the criminal ruling relates to banks only and to potential losses, and is not comparable with either. Maike Futures’ trust-unit values are one creditor’s audited fair-value estimates at 31 December 2025, unchanged in its unaudited report at 30 June 2026, built on a probability-weighted disposal model; they are not a recovery rate for the estate. Xinda’s RMB648.8m is its fair value of its share of the platform’s identifiable net assets at 31 December 2025, which differs from the RMB742m implied net assets in its December 2025 announcement because the measurement date, basis and deferred-tax treatment differ.
Reported, not confirmed. The meeting date of 28 August 2022 is inferred from Bloomberg’s 1 September report of a meeting “on Sunday”; Bloomberg’s 18 September report attributes the meeting to the Shaanxi provincial government rather than the Xi’an municipal government. The ING v ICBC facts are from Global Trade Review’s report of the Hong Kong High Court’s ruling of 23 August 2024 and Caixin’s report of the April 2023 hearing; the neutral citation [2024] HKCFI 2220 and the judgment text could not be retrieved and should be confirmed. Reports differ on the amount ING claims from ICBC (US$147.4m in GTR; US$171m in Caixin’s account of the writ); the body uses GTR’s figure for the claim and US$171m for the shipments. Caixin dates Maike’s debt crisis to October 2021; Maike’s own statements date its operating cash difficulties to September 2022. Hainan Gaoke’s ownership is from Shangyou News’s review of company records. The investor’s filing and Maike Futures’ report both give the plan-approval ruling as (2023) Shaan 01 Po 137 No. 28; the court-hosted claims ruling of 27 June 2025 carries the same number, so the body cites both by date. That claims ruling, dated 27 June, refers to claims filed up to the creditors’ meeting of 30 June; we report it as published.
Deliberately omitted. Caixin reported on 11 October 2022 that the head of ICBC’s Shaanxi branch had been removed, and later reports cited people who linked the removal to problems in international and trade-finance business, possibly involving a local private company, and described Maike as an important client of the branch. We could read only excerpts of the paywalled articles; no disciplinary or criminal action against the official has been reported, and the official is omitted. Caixin also reported that the November 2023 investigation of a former chairman of a Shaanxi provincial investment group might be connected to Maike; official notices do not mention Maike, and that is omitted. A self-media account that a bank official improperly issued bills to Maike, causing losses of several hundred million US dollars, is omitted as unverified. The first batch of confirmed claims (reported at RMB8.38bn), reported auction failures for the platform before Xinda’s bid, a reported trust size of about RMB50bn and Caixin’s reported funding gap of RMB7bn to RMB10bn are omitted because we have not seen primary or full-text sources. A Shaanxi provincial yearbook entry that appears to list Maike among major risks under discipline-commission supervision could not be opened and is omitted. Personal details of the defendant’s family are omitted as irrelevant to the risk argument.
Primary-source share. 14 of 32 footnotes are primary court, exchange, regulatory, statistical or company documents (44%). The verdict itself is unpublished, so the anchor facts on the sentence rest on Bloomberg’s wire report.
- 1 Board of Governors of the Federal Reserve System, H.10 Foreign Exchange Rates, “Chinese Yuan Renminbi to U.S. Dollar Spot Exchange Rate”, series DEXCHUS, via Federal Reserve Bank of St. Louis (FRED), observation of 16 October 2026: RMB6.6861 per US dollar; 30 June 2025: RMB7.1636. https://fred.stlouisfed.org/series/DEXCHUS. Primary official statistics. Reference rate for every US dollar equivalent in this article, which are given for scale only (see Technical notes).
- 2 Xi’an Intermediate People’s Court, Shaanxi, civil ruling (2023) Shaan 01 Po 137 No. 28 ((2023)陕01破137号之二十八), dated 27 June 2025, confirming the second batch of uncontested claims in the substantive consolidated reorganisation of Xi’an Maike Metals International Group and 25 other companies, with schedule; posted on the National Enterprise Bankruptcy Information Disclosure Platform, 14 November 2025. https://pccz.court.gov.cn/filedownloads/2025/2025-11-14/%E4%BA%8C%E6%89%B9%E7%A1%AE%E8%AE%A4%E5%80%BA%E6%9D%83%E8%A3%81%E5%AE%9A%E4%B9%A61763092977358.pdf?fn=%E4%BA%8C%E6%89%B9%E7%A1%AE%E8%AE%A4%E5%80%BA%E6%9D%83%E8%A3%81%E5%AE%9A%E4%B9%A6.pdf. Primary judicial record. Source for the 863 claims totalling RMB677.61亿 (RMB67.761bn), the 106 creditors and RMB4,518,096,344.55 confirmed, and the amounts owed to Chang’an Bank, China CITIC Financial AMC, Xiamen AMC, Agricultural Bank of China and the two largest unsecured creditors.
- 3 Xiamen Xindeco Co., Ltd. (厦门信达, SZSE: 000701), announcement 2025-93 on participation in bankruptcy reorganisation and outward investment, 18 December 2025. http://static.cninfo.com.cn/finalpage/2025-12-18/1224883555.PDF. Primary exchange filing. Source for the 2024 consolidation on grounds of highly commingled legal personality, the 30 September 2025 plan approval, the platform’s assets, the appraisal (RMB1,456.6558m against book RMB817.871m at 31 July 2025), the RMB300m price split between administrator and capital, the 75% and 25% holdings, the bankruptcy service trust, retained secured debt repayable by 30 September 2032 and Xinda’s confirmed claim of RMB359.78m.
- 4 Jiemian News (Hou Ruining), “经营性资金困难,陕西最大民企迈科集团申请预重整” (Operating cash difficulties: Shaanxi’s largest private company Maike applies for pre-restructuring), 19 February 2023. https://www.jiemian.com/article/8928626.html. Shanghai United Media Group financial outlet; it cites Maike’s 2021 interim bond report for the H1 2021 copper share and margin. Source for revenue 2018 to 2021, net profit 2018 to 2020, the 98% copper share and 1.4% gross margin in H1 2021, and total assets, liabilities and restricted assets at 30 June 2021.
- 5 Bloomberg News, “Chinese Copper Titan He Jinbi Jailed for Life Over Maike Fraud”, 26 October 2026. https://www.bloomberg.com/news/articles/2026-10-26/chinese-copper-titan-he-jinbi-jailed-for-life-over-maike-fraud. Wire report citing people familiar with the verdict. Source for the conviction, offences, life sentence, US$1bn exposure, appeal, defence arguments, unpublished judgment, the 1993 founding on a 50,000 yuan loan, the one-in-four share, warehouse borrowing and the 2022 pressures including the fall in copper prices.
- 6 All-China Federation of Industry and Commerce, “2022中国民营企业500强” (2022 China Top 500 Private Enterprises), August 2022. https://www.acfic.org.cn/ztzlhz/2022my5bq/2022my5bq_4/202208/W020221008343019801385.pdf. Official national list. Source for Maike’s rank of 48 on 2021 revenue of RMB15,987,799万 (RMB159.88bn). Maike ranked 49th in the 2021 list and is absent from the 2023 list.
- 7 Reuters (Siyi Liu and Dominique Patton), “China’s Maike Group applies to court for restructuring”, 17 February 2023, Reuters wire via Mining.com. https://www.mining.com/web/maike-group-applies-to-court-for-pre-restructuring/. Source for Maike’s statement that it imported more than 1Mt of refined copper a year, “accounting for 29% of China’s total imports in 2021”, and for the pre-restructuring application to the Xi’an Intermediate People’s Court.
- 8 Xi’an Maike Metal International Group Co., Ltd., “公开发行2018年公司债券(第二期)募集说明书” (prospectus for the public issue of 2018 corporate bonds, second tranche), Shanghai Stock Exchange, 2018. http://static.sse.com.cn/disclosure/bond/announcement/company/c/3401911701406976.pdf. Primary company filing with audited figures and Lianhe rating summary. Source for revenue 2015 to 2017, metals-trading gross margins, interest cover and its definition, current ratios, restricted assets of RMB9.419bn (40.77%), the rating agency’s risk findings, the bill-pledging business and its interest income, and settlement terms.
- 9 Caixin (Lu Yutong and Shi Yimin), “特稿|陕西最大民企迈科金属集团被诉拖欠10亿元货款 巨额债务浮出水面” (Shaanxi’s largest private company Maike sued over RMB1bn of unpaid goods; huge debts surface), 31 January 2023. https://www.caixin.com/2023-01-31/101993413.html. Leading Chinese financial publication. Source for the effect of lockdowns in Shanghai and Xi’an from March 2022 on Maike’s copper imports and property business.
- 10 International Monetary Fund, Primary Commodity Prices, “Global price of Copper”, US$ per tonne, monthly average, via Federal Reserve Bank of St. Louis, FRED series PCOPPUSDM, accessed 26 October 2026. https://fred.stlouisfed.org/series/PCOPPUSDM. Primary statistical series. Source for March 2022 (10,230.89) and July 2022 (7,544.81).
- 11 Economic Observer (Cai Yuekun), ”【金融头条】流动性危机处置进行时 陕西第一大民企迈科集团困局待解” (Liquidity crisis handling under way: Shaanxi’s largest private company Maike’s predicament unresolved), 11 February 2023. http://m.eeo.com.cn/2023/0211/577747.shtml. National business weekly, interview with He Jinbi. Source for his statements that some bank loans repaid in 2022 were hard to roll over, that the Xi’an government had set up a task force, and that the restructuring would be “在政府的主导下” (government-led) on a market-based and law-based path.
- 12 Xinhua (China Financial Information Network), State Administration of Foreign Exchange, “关于加强外汇资金流入管理有关问题的通知” (Circular on strengthening the management of foreign exchange inflows), 5 May 2013, effective 1 June 2013. https://www.cnfin.com/rmb-xh08/a/20130506/1166569.shtml. Text of a regulatory circular carried by the state news agency’s financial service. Source for the know-your-customer requirement on fictitious trade and severe penalties for arbitrage using false documents.
- 13 Global Trade Review, “Qingdao fraud probe ends with jail term”, December 2018. https://www.gtreview.com/news/asia/qingdao-fraud-probe-ends-with-jail-term/. Specialist trade-finance press, consistent with Caixin Global’s report of the Qingdao Intermediate People’s Court sentence of 10 December 2018. Source for RMB12.3bn raised through fake receipts, RMB3.6bn from 13 banks in loans, letters of credit and bank acceptance bills, and Chen Jihong’s 23-year sentence.
- 14 Global Trade Review, “ICBC hits back at ING’s copper loss suit”, 3 September 2024, reporting the Hong Kong Court of First Instance ruling of Anthony Chan J of 23 August 2024 in ING Bank v Industrial and Commercial Bank of China. https://www.gtreview.com/news/asia/icbc-hits-back-at-ings-copper-loss-suit/. Specialist trade-finance press account of a judicial ruling. Source for the 30 shipments worth US$171m from Triway to Maike between June and August 2022 on documents-against-payment terms, the US$147.4m claim, ICBC’s defence, the refusal of the stay and the judge’s observation on the collection instructions.
- 15 Caixin (Wang Xiaoqing), “荷兰ING银行起诉工行 索赔1.71亿美元” (ING sues ICBC, seeking US$171m), 26 April 2023. https://finance.caixin.com/2023-04-26/102032218.html. Leading Chinese financial publication, citing a court writ and a company-register search. Source for Triway International (裕明国际) being wholly owned by Maike with He Jinbi as a director, and for Caixin’s dating of Maike’s debt crisis to October 2021.
- 16 Bloomberg News, “ING sues legendary Chinese copper trader over $147 million debt”, 3 July 2023, Bloomberg wire via Mining.com. https://www.mining.com/web/ing-sues-legendary-chinese-copper-trader-over-147-million-debt/. Source for ING’s Hong Kong High Court claim against He Jinbi under his guarantee of debts owed by Triway International.
- 17 China Securities Regulatory Commission, Shaanxi Bureau, “关于对迈科期货股份有限公司采取责令改正并对西安迈科金属国际集团有限公司及何金碧、姜晴和、何晨、张彬、王刚采取出具警示函措施的决定” (Decision to order Maike Futures to rectify and to issue warning letters to Maike Group, He Jinbi and four officers), 陕证监措施字〔2024〕26号, dated 18 July 2024, published 19 July 2024. https://www.csrc.gov.cn/shaanxi/c104628/c7496432/content.shtml. Primary regulatory decision. Source for the warehouse-receipt pledges “无交易实质” (with no trading substance) with three Maike-controlled companies from 2021, the RMB110m fund routed into a trust loan to Maike Group, the RMB30m and RMB267m balances (4.67% and 41.19% of net assets), the non-disclosure in the 2021 and 2022 reports, and He Jinbi’s primary responsibility.
- 18 Bloomberg News, “China copper giant wins banks’ backing amid liquidity woes”, 1 September 2022, Bloomberg wire via Mining.com. https://www.mining.com/web/china-copper-giant-wins-banks-backing-amid-liquidity-woes/. Source for the bank meeting hosted by the Xi’an municipal government and the credit support and loan extensions.
- 19 Bloomberg News (Alfred Cang and Jack Farchy), “Tycoon running a quarter of China’s copper trade is on the ropes”, 18 September 2022, Bloomberg wire via Mining.com. https://www.mining.com/web/tycoon-running-a-quarter-of-chinas-copper-trade-is-on-the-ropes/. Source for BHP and Codelco pausing sales and diverting cargoes, and ICBC Standard Bank moving copper backing its Maike loans out of China.
- 20 Reuters, citing Bloomberg News, “JPMorgan, ICBC Standard pull back from Chinese metals traders after Maike crisis”, 16 September 2022, via Yahoo Finance. https://finance.yahoo.com/news/jpmorgan-icbc-standard-pull-back-090427777.html. Source for the cuts to financing of other Chinese metals traders.
- 21 Xiamen Xindeco Co., Ltd., announcement 2023-7 on arbitration proceedings, 20 January 2023. http://static.cninfo.com.cn/finalpage/2023-01-20/1215666374.PDF. Primary exchange filing. Source for the four arbitrations accepted on 16 January 2023 (RMB106.55m, 107.18m, 108.74m and 762.87m), He Jinbi as respondent, and the guarantees capped at RMB2.8bn and RMB2.0bn.
- 22 Xiamen Xindeco Co., Ltd., announcement 2023-41 on progress in major arbitration, 5 June 2023. http://static.cninfo.com.cn/finalpage/2023-06-05/1216985460.PDF. Primary exchange filing. Source for the partial award, the transfer of 179,573,082 Qingtongxia Aluminium shares (12.86%) and the valuation of RMB96,719.47万 (RMB967.19m) at 31 August 2022.
- 23 Shangyou News, “陕西最大民企迈科集团被受理破产重整 申请人为西安本地国企子公司” (Shaanxi’s largest private company Maike accepted for bankruptcy reorganisation; petitioner is a Xi’an state-owned subsidiary), 14 November 2023, via Sina Finance. https://finance.sina.com.cn/jjxw/2023-11-14/doc-imzuqitt3630169.shtml. Chongqing Daily Group outlet. Source for the Xi’an Intermediate People’s Court ruling (2023)陕01破申216号 of 13 November 2023 accepting Hainan Gaoke Trading’s petition, and Hainan Gaoke’s ownership by Xi’an Gaoke Group.
- 24 Bloomberg News (Alfred Cang), “Chinese copper tycoon goes missing, believed to be detained by police”, 9 October 2023, Bloomberg wire via Mining.com. https://www.mining.com/web/chinese-copper-tycoon-goes-missing-believed-to-be-detained-by-police/. Source for executives losing contact with He and their belief that police had taken him for questioning in Shaanxi.
- 25 Xiamen Xindeco Co., Ltd., 2025 Annual Report, 24 April 2026, section on business combinations not under common control (pp. 262 to 263) and income statement notes. http://static.cninfo.com.cn/finalpage/2026-04-24/1225165175.PDF. Primary audited company filing. Source for the November 2022 arbitration claim of RMB125.82m against Maike and Maike Investment and the December 2022 award, the acquisition date of 31 December 2025, the RMB300m cost, the RMB648,826,097.22 fair value of its share of identifiable net assets, the RMB348,826,097.22 excess recognised in non-operating income, and the conversion of its claims into trust units.
- 26 Maike Futures Co., Ltd. (NEEQ: 870593), 2025 Annual Report (audited), published 24 April 2026, notes on other non-current financial assets and on funds occupied by the controlling shareholder. http://notice.10jqka.com.cn/api/pdf/a27aface3c3a611.pdf (mirror of the NEEQ filing). Primary audited company filing. Source for the 83.17% holding, the trust’s 15-year term with operation in years 1 to 10 and disposal in years 11 to 15, the conversion of claims into ordinary and priority units on 24 December 2025, the ordinary units carried at RMB0 against an original value of RMB160,387,937.45, and the priority units carried at RMB58,207,613.28 against an original value of RMB110,000,000. The unaudited 2026 interim report (https://pdf.dfcfw.com/pdf/H2_AN202608261828473899_1.pdf) carries both at the same values at 30 June 2026.
- 27 The Paper (澎湃新闻), report of the first-instance judgment in the Wuhan Kingold fraud case, 1 June 2024. https://m.thepaper.cn/newsDetail_forward_27560962. Shanghai United Media Group outlet quoting the Wuhan Intermediate People’s Court judgment of 28 May 2024. Source for Jia Zhihong’s life sentence for contract fraud and bribery offences, the RMB25.345bn raised from 15 institutions (another passage of the same report says 16) and the 105.77 tonnes of copper-alloy “gold”.
- 28 Bloomberg News, “Rogue China aluminum trader gets life in jail after $1 billion fraud”, 11 March 2025, Bloomberg wire via Gulf News. https://gulfnews.com/world/asia/rogue-china-aluminum-trader-gets-life-in-jail-after-1-billion-fraud-1.500057216. Source for Chen Xi’s life sentence, the duplicated inventory receipts, the repurchase structure and the RMB7.6bn raised.
- 29 Associated Press (Chan Ho-him), “Chinese court sentences founder of troubled property developer Evergrande to life in prison”, 20 August 2026, via WJXT News4Jax. https://www.news4jax.com/news/2026/08/20/chinese-court-sentences-founder-of-troubled-property-developer-evergrande-to-life-in-prison/. Source for Hui Ka Yan’s life sentence by the Shenzhen Intermediate People’s Court.
- 30 Singapore Police Force, “Founder of Hin Leong Trading sentenced and jailed for cheating and instigating forgery”, 18 November 2024. https://www.police.gov.sg/media-hub/news/2024/20241118_founder_of_hin_leong_trading_sentenced_and_jailed_for_cheating_and_instigating_forgery. Primary government record. Source for Lim Oon Kuin’s 17.5-year sentence for cheating HSBC and instigating forgery, and the US$111.7m HSBC disbursed on two applications.
- 31 Manifold Times, “Singapore: Hin Leong founder OK Lim gets jail term slashed to 13.5 years”, 5 March 2026. https://www.manifoldtimes.com/news/singapore-hin-leong-founder-ok-lim-gets-jail-term-slashed-to-13-5-years/. Specialist marine-fuels press. Source for the High Court’s reduction of the sentence on appeal on 4 March 2026, with the conviction upheld.
- 32 International Chamber of Commerce, “ICC Trade Register affirms trade finance’s decade-long low risk profile”, 11 June 2019. https://iccwbo.org/news-publications/news/icc-trade-register-affirms-trade-finances-decade-long-low-risk-profile/. Primary industry statistics body. Source for obligor-weighted default rates by product: 0.37% on import letters of credit and 0.76% on import and export loans, 2008 to 2018.
Not investment research. This is commentary and analysis. It is not a recommendation and not an inducement to buy, sell or hold any security or commodity.